Last updated: 9 June 2026
By Stiv · Design, technology and personal finance
This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
Happy with the safety answer already?
The Zopa Biscuit referral is live again and pays £20, and our referral page sets out the steps and the current terms.
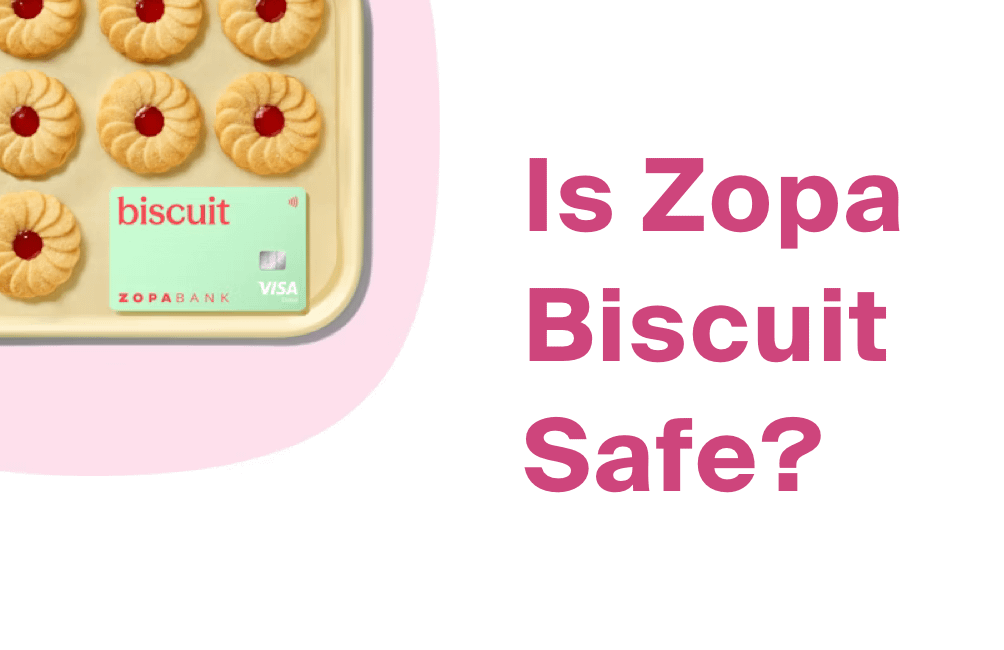
Zopa's Biscuit bank account has made waves by letting you choose your own perk: 2.75% AER interest on your balance, 3% cashback on eating out, or 3% cashback on bills. But before handing over your money, you probably want to know: is Zopa Biscuit safe? The short answer is yes. Zopa is a fully licensed UK bank, regulated by the FCA and PRA, and your deposits are protected up to £120,000 by the Financial Services Compensation Scheme (FSCS). Below, we break down exactly what that means and what you should know before opening an account.
Is Zopa Biscuit safe? The quick answer
Yes, Zopa Biscuit is safe. Zopa Bank Limited is authorised by the Prudential Regulation Authority (PRA) and regulated by both the PRA and the Financial Conduct Authority (FCA). Eligible deposits are protected up to £120,000 per eligible person per UK-authorised bank, building society or credit union by the FSCS (since 1 December 2025). This limit rose from £85,000 on 1 December 2025, so you now get significantly more cover than before.
In practical terms, if Zopa Bank Limited were to fail, the FSCS would reimburse you up to that £120,000 ceiling. This is the same level of protection you get with any major high-street bank. So from a regulatory standpoint, your money is just as safe in Biscuit as it would be in Barclays, HSBC or Lloyds.
Who regulates Zopa?
Zopa Bank Limited holds a full UK banking licence. Specifically, the PRA authorises it to accept deposits, while the FCA oversees its conduct with customers. You can verify this yourself on the FCA's public register (firm reference number 800542).
Because of this dual regulation, Zopa must meet the same capital, liquidity and conduct standards as every other UK bank. In addition, the bank undergoes regular supervisory reviews. This is worth noting because some fintech apps (such as e-money providers) do not offer FSCS protection at all. Zopa does, and that makes a meaningful difference to your safety.
What does Zopa Biscuit offer?
Now that we have covered the safety side, here is a quick look at what the account actually includes. For a full breakdown, check out our Biscuit bank account review.
1% AER as standard, or 2.75% AER if you choose interest
Every Biscuit account earns 1% AER (1% gross, variable) on the balance. Choose the interest benefit and that rises to 2.75% AER (2.72% gross, variable), with no cap on how much you can earn. Both rates are variable, so they can move. Source: Zopa.
3% cashback on Direct Debits, or on eating out
Biscuit pays 3% cashback on up to £150 of Direct Debits a month, which caps out at £4.50 a month, or roughly £54 a year. Alternatively, you can point the same 3% at restaurants, takeaways and bakeries instead. You only get one benefit at a time, though, so cashback and the boosted interest cannot be stacked. Source: Zopa fees and useful information.
The 7.10% Regular Saver is closed to new customers
This used to be the standout feature, but Zopa closed it to new customers during 2026. Existing pots keep running, while new saving happens in the separate Smart Saver account, where Boosted notice pots pay up to 3.55% AER (variable) and fixed-term pots pay up to 4.65% AER. Source: Zopa Smart Saver page.
Fee-free spending abroad
Biscuit uses the real Visa exchange rate with no added fees from Zopa. It works well as a travel card alongside your main account. Note that ATM withdrawal fees may apply when using your card abroad.
Easy access savings
Zopa offers easy access Access pots paying 2.95% AER (2.91% gross, variable) to all customers, plus an Access ISA at 3.25% AER (3.20% gross, variable). These sit outside the Biscuit current account balance. Source: Zopa easy access savings page.
Smart app features
On top of all that, the Zopa app includes instant notifications, card freeze controls, Apple Pay and Google Pay, spending analytics and the ability to connect external bank accounts.
What are the drawbacks?
No account is perfect, and Biscuit has some notable gaps you should consider before signing up.
No cash or cheque deposits
Zopa is entirely digital. If you regularly handle cash, this will not work as your only bank account.
No full CASS switching support
As of June 2026, Zopa does not fully support the Current Account Switch Service. You will need to move Direct Debits across manually if you want to earn cashback on them.
Introductory rates are time-limited
Every headline rate here is variable, so the 2.75% interest and the 3% cashback can both be cut. Zopa also reserves the right to change which benefits it offers.
Digital-only support
There are no branches. Everything runs through the app or in-app chat. Zopa's customer support operates Monday to Saturday.
How does Zopa Biscuit compare to alternatives?
Biscuit sits in a competitive space alongside other digital current accounts. For instance, if your household bills exceed around £550 per month, Santander Edge may return more cashback despite its £2 monthly fee. Meanwhile, Chase offers 2% cashback on eligible everyday card spending categories (capped at £20 per month, with monthly qualification criteria from June 2026), which suits a different spending pattern. We have compared the two head to head in our Zopa Biscuit vs Chase guide if you want the full picture.
For a free account with no monthly fee, the choice between 2.75% on your balance and 3% cashback still holds up well against the other digital banks.
How to open a Zopa Biscuit account
Opening the account takes about five minutes. You need to be a UK tax resident aged 18 or over. Zopa runs a soft credit search during sign-up, so applying will not affect your credit score.
The Zopa Biscuit refer-a-friend offer is live again and pays £20. Open Biscuit through the link, then make at least three card transactions within 30 days. The steps and the current terms sit on our Zopa Biscuit referral page. T&Cs apply.
Open a Biscuit accountFAQs
Is Zopa Biscuit safe for large balances?
Eligible deposits are protected up to £120,000 per eligible person per UK-authorised bank, building society or credit union by the FSCS (since 1 December 2025) with Zopa Bank Limited. If you hold more than that with Zopa, the excess would not be covered. For joint accounts, each holder gets £120,000 of protection, giving a combined total of £240,000.
Will applying for Zopa Biscuit affect my credit score?
No. Zopa uses a soft credit search during the application process, which does not appear on your credit report and will not affect your score.
Can I use Zopa Biscuit as my main bank account?
You can, although it works best as a secondary account. Because there are no cash deposits and no full CASS switching, most people pair Biscuit with a traditional current account.
Does Zopa charge any monthly fees?
No. The Biscuit account is completely free to open and use. There are no monthly fees or hidden charges.
What happens after the first 12 months?
The rates are variable from the start. Zopa will tell you before anything changes, but the interest and cashback rates can go up or down.
Can I deposit cash into Zopa Biscuit?
No. Zopa is a digital-only bank and does not accept cash or cheque deposits.
Explore more from CoolCuration
- Biscuit bank account review: our full verdict on the account's features, rates and whether it is worth it in 2026.
- Monzo vs Biscuit: a side-by-side comparison of two popular free digital bank accounts.
- Zopa Biscuit vs Chase: cashback, interest and fees compared head to head.
- Chip savings app: another way to grow your savings automatically.
- Gift guide for techies: cool gadgets and gear for anyone who loves technology.
This article is for general information only and does not constitute financial advice. Banking products change frequently, and your personal circumstances may affect what is suitable for you. Always check the latest details with the provider before applying. CoolCuration may earn referral commissions which help support the site at no extra cost to you.
What's trending
Recent posts
- Philips OneBlade Review UK: 4/5 After Five Years
 Five years with the same Philips OneBlade. One handle, a new blade every four months, and blades that work out at £1.65 a month. Here is what wore out, which blade I stopped buying, and the one design flaw that will eventually kill it. #philipsoneblade #grooming #shaving #ukreviews #coolcuration
- Best Smart Home Starter Kit UK 2026: Apple, Google or AlexaThree ways into a smart home and one box you replace if you change your mind. Apple, Google and Alexa priced side by side, plus the Matter kit that works with all three.
- Best Refurbished AirPods UK 2026: Where to Buy and What It SavesRefurbished AirPods UK prices at Back Market, Amazon Renewed and Apple, set against the cheapest new price at Argos, AO and Currys.
No Comments.