Last updated: 6 September 2026
By Stiv · Design, technology and personal finance
This is an opinion piece. Views expressed are the author's own and do not constitute professional advice.
Cool Factor: 3/5
This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
Thinking of opening Biscuit?
The refer-a-friend bonus is live again at £20, and our Zopa Biscuit referral page carries the steps and the current terms.
This Biscuit bank account review takes a look at Zopa's free current account after months of real-world use. Zopa rebuilt it during 2026, so it now pays 1% AER (variable) as standard and lets you pick one benefit on top: 2.75% AER (variable) interest, 3% cashback on eating out, or 3% cashback on bills. There is a free Caffè Nero drink every month as well. But does it actually deliver? We break down what works, what falls short and whether it deserves a spot on your phone in 2026.
What is the Biscuit bank account?
Biscuit is Zopa's first current account, launched in mid-2025 and built entirely around the Zopa app. Think of it as a digital-only alternative to Monzo or Starling, but with a heavier focus on earning returns rather than budgeting tools. There are no monthly fees, no hard credit checks to open it, and the whole sign-up takes about five minutes.
Every account earns 1% AER (1% gross, variable) on the balance. Then you choose one benefit each month, and you can change that choice whenever you like. The options are 2.75% AER (2.72% gross, variable) interest on your balance, 3% cashback on up to £150 a month of dining spend, or 3% cashback on up to £150 a month of Direct Debits. Each cashback option is capped at £4.50 a month, so about £54 a year. You also get a free Caffè Nero drink every month and fee-free card spending abroad at the real Visa exchange rate. Zopa Bank Limited is authorised by the Prudential Regulation Authority and regulated by the FCA (firm reference number 800542, FCA register). Eligible deposits are protected up to £120,000 per eligible person per UK-authorised bank, building society or credit union by the FSCS (since 1 December 2025) with Zopa Bank Limited. Sources: Zopa; Zopa fees and useful information.
The Zopa Biscuit refer-a-friend offer is live again and pays £20. Open Biscuit through the link, then make at least three card transactions within 30 days. The steps and the current terms sit on our Zopa Biscuit referral page. T&Cs apply.
First impressions of Biscuit
Opening the account is painless. You download the Zopa app, answer a few standard questions, snap a photo of your ID and take a selfie. Importantly, Zopa runs only a soft credit search, so it will not affect your credit score. Within minutes, your account is live and you can start setting up Direct Debits and savings pots.
The app itself feels clean and minimal. It lacks the social features and spending breakdowns that Monzo users love, but it makes up for that with straightforward access to savings tools. If you prefer simplicity over bells and whistles, you will probably appreciate the approach.
Biscuit bank account review: the detail
The biggest change this year is what left. Zopa closed the 7.10% AER regular saver to new customers, and the old 2% balance rate went with it. Existing accounts have not been moved across yet, so mine still shows 2.00% AER on the balance and a live 7.10% pot with a monthly auto-save running into it. Savings now sit in Zopa's separate Smart Saver account instead, where Access pots pay 2.95% AER (variable), Boosted notice pots pay up to 3.55% AER (variable) and fixed-term pots pay up to 4.65% AER. There is an Access ISA at 3.25% AER (variable) too. Source: Zopa Smart Saver.
What replaced it is decent, though. Pick the interest benefit and the balance rate rises to 2.75% AER, with no cap on the amount that earns it. Most high-street current accounts still pay nothing, so that is money on cash which would otherwise sit idle. The rate is variable, so it can move. Source: Zopa.
Cashback is still the weakest part of the package. The rate went up to 3%, but it only applies to £150 of spending a month, so the ceiling is £4.50 a month or roughly £54 a year. Worse, you cannot take cashback and the boosted interest together, because the benefits are a menu rather than a stack. If you pay significant bills, a paid account like Santander Edge could return more through its own cashback scheme.
Abroad spending is fee-free on card payments at the real Visa exchange rate. ATM withdrawal fees may apply when using your card abroad.
Value for money
So what does that add up to? On the average UK current account balance of about £4,460, the 2.75% option pays roughly £120 a year. Take cashback instead and the most you can earn is £54, and only if you route £150 of qualifying spending through the account every month. Whichever you pick, the free Caffè Nero drink adds up to something too.
Either way, that is impressive for a completely free account. By comparison, the Chase current account offers 2% cashback on eligible spending categories (capped at £20 per month, with monthly qualification criteria from June 2026) but no interest on your main balance, while Monzo's standard account pays nothing on your main balance at all. If you want a head-to-head, our Biscuit vs Chase comparison goes deeper.
What holds it back
First, Zopa still does not fully support the Current Account Switch Service (CASS). That means you will need to move Direct Debits over manually, which is a hassle. Second, this is a digital-only account with no cash or cheque deposits. If you regularly handle physical money, Biscuit cannot be your primary bank. Finally, every headline rate here is variable, so the 2.75% and the 3% cashback can both be cut.
The app has come a long way
One thing deserves saying plainly: the app is far more finessed than it was at launch. The home screen leads with the account card and a clean row of Add, Move and Send buttons, activity sits below it, and pots follow underneath. Moving money is two taps and a picker rather than a trek through menus. Save and Invest puts the whole savings picture on one screen, with each pot and its rate on the same line.
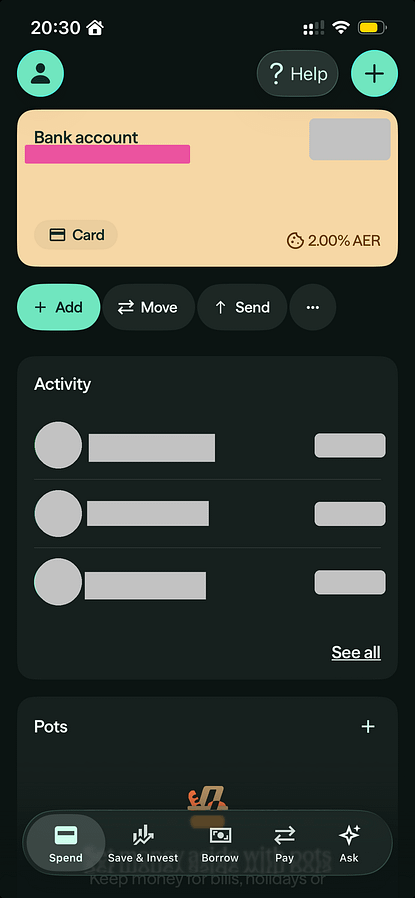
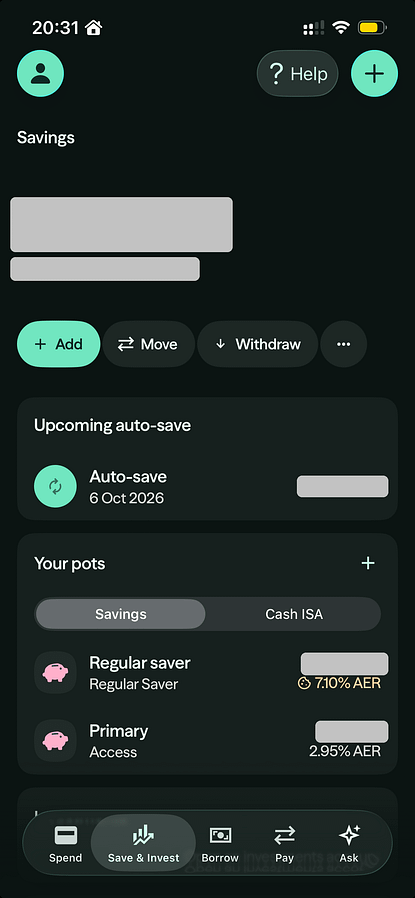
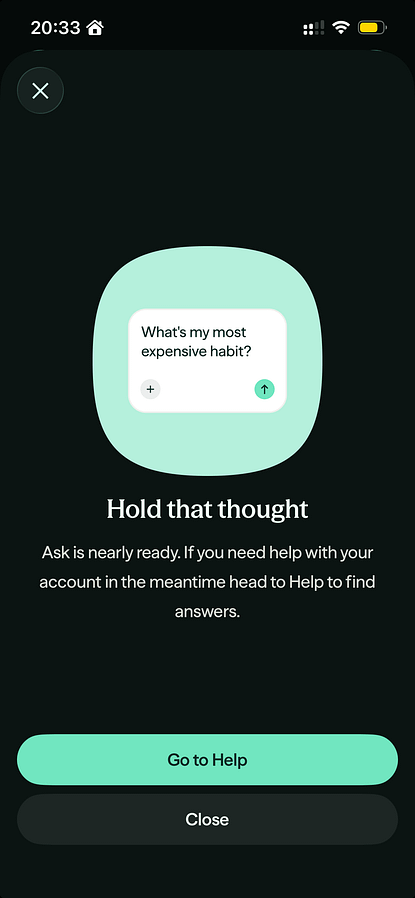
The 2026 app: the home screen, the savings pots view, and the Ask tab that is still a placeholder. Balances and payee details redacted.
One oddity survives, though. The Ask tab, which is meant to be Zopa's banking AI, is still just an intro screen. Tap it and you get a "Hold that thought" panel saying Ask is nearly ready, with a button through to Help. Shipping a tab in the main navigation that does nothing yet is a strange call, and it is the one part of the app that still feels unfinished.
The verdict
Cool Factor
★★★☆☆
3 out of 5
Biscuit still works well as a secondary 'satellite' account alongside your main bank. One approach is to park spare cash there on the 2.75% benefit and leave it alone. Another is to run your Direct Debits through it for the cashback. You cannot do both at once, though, which is the part that stings after the old set-up. It is not trying to replace Monzo or Starling as an all-in-one banking app, and that is fine.
Ready to give it a try? The refer-a-friend bonus is live again at £20, and the link below has the steps. T&Cs apply.
Prefer a bank offer that is still running?
Zopa's Biscuit bonus is back at £20, and Monzo's offer is live too.
Overall, this is a 3/5 Cool. The account still does its job, and 2.75% on your balance with fee-free spending abroad is a fair deal for nothing a month. It has slipped from last year, though, because the 7.10% regular saver that made it remarkable is closed to new customers, the cashback stops at £54 a year, and you have to choose one benefit rather than collect them all. Solid, then, but no longer the standout free account it was.
Biscuit bank account review: FAQs
Is the Biscuit bank account safe?
Yes. Zopa Bank Limited is authorised by the PRA and regulated by the FCA. Eligible deposits are protected up to £120,000 per eligible person per UK-authorised bank, building society or credit union by the FSCS (since 1 December 2025). You can verify Zopa Bank Limited's registration on the FCA register (FRN 800542).
Can I use the Current Account Switch Service?
Not fully. As of June 2026, Zopa does not support CASS, so you will need to set up Direct Debits manually if you want to earn the cashback perk.
How much can I realistically earn with Biscuit?
It depends which benefit you pick. On a £4,460 balance the 2.75% interest option pays about £120 a year, while the cashback options top out at £54 a year. You cannot run both at the same time.
Does opening Biscuit affect my credit score?
No. Zopa performs a soft credit search only, which does not appear on your credit file or affect your score.
Can I deposit cash or cheques?
No. Biscuit is entirely digital. If you regularly handle physical money, you will need to keep another account for that purpose.
What happened to the 7.10% Regular Saver?
Zopa retired it during 2026. Savings now sit in the separate Smart Saver account, where Access pots pay 2.95% AER (variable) and fixed-term pots pay up to 4.65% AER.
How does Biscuit compare to Monzo?
Biscuit wins on savings returns, while Monzo excels at budgeting tools and spending insights. We cover this in detail in our Monzo vs Biscuit comparison.
More from CoolCuration
- Best savings accounts in the UK: compare the top rates and find the right home for your money.
- Chase refer-a-friend code: another strong free bank account with cashback perks worth comparing.
- Emma budgeting app: track all your accounts and subscriptions in one place.
- Gift guide for techies: smart gadgets and gear for the tech-obsessed.
- Kindle Paperwhite: the best e-reader for getting lost in a good book.
This article is for information only and does not constitute financial advice. Always check the latest rates, terms and eligibility directly with Zopa before applying. Rates and offers mentioned are correct at the time of writing but may change. CoolCuration may earn a referral reward if you open an account using links on this page, which helps support the site at no extra cost to you.
What's trending
Recent posts
- iPhone 18 Pro and iPhone Ultra: What to Expect
 Last updated: 7 September 2026iPhone 18 Pro By Stiv · Design, technology and personal finance Nobody outside Apple knows whether a phone called the iPhone 18 Pro exists. What Apple has confirmed is a date. Wednesday 9 September, 6pm UK time, at an event it is calling Surprise and shine. Everything else you have read… Read more: iPhone 18 Pro and iPhone Ultra: What to Expect
- Best Gifts Under £50 UK: 14 Design-Led PicksFourteen gifts between £25 and £50, from a self-build 35mm SLR to a Hockney tray. Every price checked at the shop on 4 September 2026.
- Best Audiobooks September 2026: 10 UK Listens RankedLast updated: 4 September 2026 By Tristan · Arts, exhibitions and creative culture AudiobooksSeptember 2026 Edit Ten listens, and one of them is forty hours Here is my pick of the best audiobooks September 2026 is putting in front of UK ears, and the range is wider than usual. Marlon James arrives with a Booker… Read more: Best Audiobooks September 2026: 10 UK Listens Ranked

No Comments.