Last updated: 17 September 2026
By Stiv · Design, technology and personal finance
I’ve been overpaying my Nationwide mortgage since October 2021, mostly £100 a month through Sprive, alongside manual payments to the lender. Everything here comes from almost five years of doing it.
This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view. This is information, not financial advice, and CoolCuration is not authorised by the Financial Conduct Authority.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Sprive sign-up bonus
If an app would help you stay consistent, our referral page always carries the latest Sprive offer and how to claim it.
Claim the current Sprive offer
Mortgage overpayment in the UK means paying your lender more than the monthly amount it asks for, so the balance and the interest charged on it fall sooner. Kept inside your lender’s allowance, it can take years off the term. Go over the allowance on a fixed deal and an early repayment charge can wipe out the saving.
Run your own numbers first
Put in your balance, your rate, the years left and a lump sum, a monthly overpayment or both. The calculator shows the interest you would avoid and your new mortgage-free date. Tick one box and it runs the same money through a savings account to show which wins.
How the mortgage guides fit together. The overpayment rules and the full list of guides live here. Save thousands on your mortgage is about cutting what the mortgage costs. Pay off your mortgage faster is about clearing it sooner. Mortgage overpayment savings works through what an overpayment would actually save.
Every mortgage overpayment guide, by question
Start here
Overpaying: the sums
Remortgaging
Overpay or invest
Tools and apps
Rates now
Bank Rate is 3.75%. The Bank of England held it on 17 September 2026 by six votes to three, with three members voting for a rise to 4%. The next decision is due on 5 November 2026.
What is mortgage overpayment?
A mortgage overpayment is any payment you make on top of your normal monthly mortgage payment. The aim is to reduce your outstanding balance faster than the original repayment schedule requires.
Because mortgage interest is calculated on your remaining balance, reducing that balance earlier means less interest is charged going forward. Over time, that can translate into a shorter mortgage term, a lower total interest bill, or both.
Overpayments come in two forms: regular overpayments (for example, an extra £50 or £100 each month) and lump sums (bonuses, tax refunds, inheritance). You can also combine the two.
How mortgage overpayments save you money
Most UK mortgages charge interest daily or monthly on the outstanding balance. When you make an overpayment, the balance drops immediately. As a result, future interest is calculated on a smaller amount, and over time that saving compounds in your favour.
According to MoneyHelper, even modest overpayments made early in your mortgage term can have a significant impact because you are typically paying more interest in those early years. That does not mean you should overstretch, but it does explain why starting sooner tends to be more powerful than starting later.
Overpayment limits in the UK
Most UK mortgage products allow overpayments up to a set percentage each year without penalty. According to MoneyHelper and the Sprive FAQ, many lenders allow up to 10% of the outstanding balance per year without penalty. However, this threshold varies: some lenders allow 15% or more, others cap at 5%, and the start date for the annual period also differs between providers.
Before you overpay, check these three things with your lender:
- Is the limit based on the original balance or the current balance?
- Does the allowance reset annually or per deal period, and from which date?
- Does the lender count regular monthly overpayments towards the allowance alongside lump sums?
Never assume. Always confirm via your mortgage offer document, lender portal, or a direct call. Getting this wrong can trigger Early Repayment Charges that cancel out your savings.
Early Repayment Charges (ERCs) explained
Early Repayment Charges are fees your lender applies if you repay more than your allowed amount, or exit your mortgage deal early. ERCs typically apply during fixed-rate periods and some tracker deals with exit penalties.
The charges can be significant, often 1% to 5% of the amount overpaid. In some cases, a single overpayment that breaches your allowance can cost more than the interest you would have saved. If you are on a fixed rate, always overpay within your allowance only, unless you have calculated that paying the charge still works out cheaper overall.
For a focused breakdown of how overpayment limits and ERCs work specifically within the Sprive app, our Sprive overpayment rules guide covers the detail.
Does overpaying reduce the term or the payment?
This is one of the most misunderstood parts of mortgage overpayment in the UK. Depending on your lender, extra payments may automatically reduce the mortgage term, reduce your monthly payment amount, or in some cases you can choose which one applies.
If your goal is to become mortgage-free sooner, reducing the term is usually more effective because it cuts both the time and the total interest paid. However, reducing the monthly payment can provide useful breathing room if your finances are tight.
Check how your lender applies overpayments by default and whether you can change this setting. Nationwide, for instance, lets customers adjust their overpayment preference through Mortgage Manager, while other lenders require a phone call.
Regular overpayments vs lump sums
Regular overpayments
Regular overpayments are best for building a consistent habit and smoothing the impact on your monthly budget. Even £25 to £100 per month can make a meaningful difference over a 20 to 25 year term. The key advantage is predictability: you know exactly what is going out each month and can plan around it.
Lump sum overpayments
Lump sums work well for bonuses, inheritance, or savings you are confident you will not need in the short term. However, always keep an emergency buffer before making a large lump sum payment. Overpaying your mortgage and then relying on credit cards for the next unexpected bill often ends up costing more in interest than you saved.
When overpaying may not be the best move
Overpaying your mortgage is not always the smartest use of spare cash. Four situations call for caution:
- You have high-interest debt elsewhere (credit cards, personal loans). Clearing those first almost always saves more.
- Your mortgage rate is low and your savings could earn a higher return after tax. This is a trade-off: as a reference point, the Bank of England held the base rate at 3.75% on 17 September 2026 (a 6 to 3 vote, with three members wanting a rise to 4%), and the next decision is due on 5 November 2026. My Bank of England base rate page tracks every decision and what it means for overpayers. Whether overpaying beats saving depends on your specific mortgage rate versus the savings rate available to you.
- You have no emergency fund. Three to six months of essential expenses in accessible savings should come first.
- You expect to need access to the money soon. Mortgage overpayments are illiquid; once the money is in your mortgage, getting it back typically requires a remortgage or further advance.
If you are weighing up whether spare cash should go to your mortgage or into investments, we have written about that trade-off in detail: overpay mortgage or invest. Note that if investing is part of that comparison, capital is at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results. Tax treatment depends on the individual circumstances of each client and may be subject to change in future.
Overpaying on a fixed-rate mortgage
Fixed-rate mortgages are where most people trip up with overpayments. The allowance is usually tighter, ERCs are more punishing, and the stakes of getting it wrong are higher.
Three practical rules to follow:
- Stay within your annual overpayment allowance at all times.
- Track cumulative overpayments throughout the year, not just individual payments.
- Avoid making one large payment at the end of the year without checking your running total first.
If your fixed deal is ending soon, it can sometimes make sense to wait and apply overpayments after you switch products, when ERCs no longer apply.
Tools that help you overpay consistently
Some people manage overpayments manually with a standing order to their lender, and that works perfectly well. Others prefer tools that automate the process or flex with their spending so consistency is not entirely dependent on willpower.
Sprive is one example of a UK app designed for this. It connects to your bank via Open Banking, helps you set aside amounts you can afford, and routes them towards mortgage overpayments. It also offers cashback on in-app shopping that feeds into your overpayment pot. I have been using it with my Nationwide mortgage since October 2021, overpaying around £100 per month through the app alongside other payments. For the full opinion-based verdict, our Sprive mortgage app review covers the experience honestly. For a walkthrough of the setup mechanics, our how the Sprive app works guide has the step-by-step detail.
Sprive isn’t the only route. The mortgage overpayment apps comparison sets it against Chip, Plum, Emma and TopCashback. Every Sprive article is on the Sprive guides hub.
If you would like to try Sprive, the current sign-up bonus and claiming steps are on our referral page:
Get the current Sprive referral bonus
Sprive Limited is an appointed representative of Connect IFA Ltd and New Leaf Distribution Limited, both authorised and regulated by the Financial Conduct Authority (Sprive FRN 919863; Connect IFA FRN 441505; New Leaf Distribution FRN 460421). Money in the Sprive wallet is held by PrePay Technologies Limited (FRN 900010) as safeguarded e-money, not FSCS-protected. CoolCuration is not authorised by the FCA and does not give personalised advice.
A simple mortgage overpayment checklist
Before you start overpaying, run through these five checks:
- Confirm your annual overpayment allowance and when it resets.
- Check whether ERCs apply to your current product.
- Find out how your lender applies overpayments (term reduction vs payment reduction).
- Make sure you have an emergency buffer in place first.
- Start small and increase later once you are comfortable.
For the broader strategy beyond overpayments alone, including rate switching, lump sum timing, and remortgaging, our how to pay off your mortgage faster guide covers all seven steps in order. And for a wider look at the everyday savings that can free up cash for overpayments, our save thousands on your mortgage guide covers the cost side: the rate, the SVR and the household leaks.
Common mistakes to avoid
- Overpaying without checking your allowance or ERCs first.
- Draining your savings completely and then borrowing at a higher rate for emergencies.
- Not tracking cumulative overpayments across the year.
- Assuming all lenders handle overpayments the same way.
- Forgetting to check whether overpayments reduce the term or just the monthly payment.
FAQs
How much can I overpay on my mortgage each year?
Most UK lenders allow overpayments of up to 10% of the outstanding balance per year on fixed-rate products without penalty, according to MoneyHelper and Sprive's own published guidance. Tracker and variable-rate mortgages often allow unlimited overpayments, but always check your specific deal. The allowance, threshold basis, and reset date vary between lenders and products.
Do mortgage overpayments reduce my term or my monthly payment?
It depends on your lender. Some reduce the term by default, others reduce the monthly payment, and some let you choose. If your goal is to pay off your mortgage sooner, term reduction is usually more effective. Contact your lender to check and change the default if needed.
Is it better to overpay my mortgage or put money into savings?
As a general rule, if your mortgage rate is higher than the after-tax interest you would earn on savings, overpaying wins. If your savings rate is genuinely higher, saving may make more sense. We explore this trade-off in detail in our overpay mortgage or invest guide. If investments are part of the comparison, capital is at risk and the value of investments can go down as well as up.
What happens if I overpay more than my allowance?
You will likely face an Early Repayment Charge, which can be several percent of the excess amount. In some cases this can cost more than the interest you would have saved. Always check your cumulative total before making additional payments, especially towards the end of your allowance period.
Can I get my overpayment money back?
Generally, no. Mortgage overpayments are illiquid. Once the money is applied to your balance, getting it back usually requires a remortgage or further advance from your lender, both of which carry costs and are at your lender's discretion. Some lenders offer a borrow-back or payment holiday facility if you have previously overpaid, but this varies. Always keep an emergency fund before committing to overpayments.
More from CoolCuration
- Chip app: a savings app that moves spare cash automatically, handy for building an overpayment pot before it goes to the lender.
- Octopus Energy: switching and referral details for the supplier, since the energy bill is often the quickest household cost to change.
- Cut household bills UK: seven ways to trim monthly outgoings and free up cash for overpayments.
- Gifts under £25: presents that leave the overpayment budget alone.
This article is for informational purposes only and does not constitute financial advice. Your home may be repossessed if you do not keep up repayments on your mortgage. Always check your mortgage terms, overpayment limits, and early repayment charges before making changes. If investments are discussed in this context, capital is at risk: the value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results. Tax treatment depends on the individual circumstances of each client and may be subject to change in future. Consult a qualified financial adviser if you are unsure. CoolCuration is not authorised by the Financial Conduct Authority.
What's trending
Recent posts
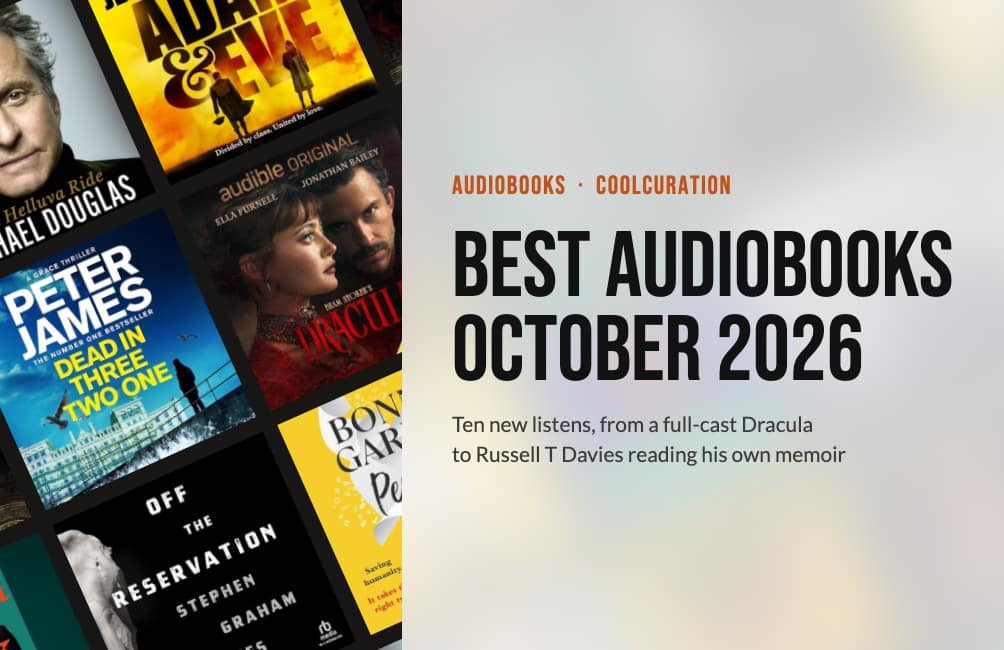
- Best Audiobooks October 2026: 10 UK Listens Ranked
 Ten new audiobooks for October 2026, from a full-cast Dracula with Jonathan Bailey to Russell T Davies reading his own television memoir.
- Louis Fratino at David Zwirner ReviewLast updated: 4 October 2026 By Tristan · Arts, exhibitions and creative culture This is an opinion piece. Views expressed are the author's own and do not constitute professional advice. Exhibition reviewMayfair Saunas, subway cars and a lot of skin in Mayfair Louis Fratino at Zwirner is the American painter's first solo show in London,… Read more: Louis Fratino at David Zwirner Review
- What Is a Sprive Boost? Seven Days, and What It Actually PaysA Sprive boost lifts your cashback rate for seven days, and it arrives on its own. What mine paid, and why Supercharge is a display toggle rather than extra cashback.
No Comments.