Last updated: 2 October 2026. Every rate below came off my own Sprive app that day, with Supercharge switched off.
By Stiv · Design, technology and personal finance
Sprive has been pushing £100 a month at my Nationwide mortgage since October 2021. Across nearly five years I have watched the rates in the Shop tab move. A boost has landed on my account more than once, so I know what one looks like.
Affiliate disclosure: This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
This is not financial advice. CoolCuration is not authorised by the Financial Conduct Authority, and I write here as a Sprive user rather than as an adviser. Check your own mortgage terms, and speak to a qualified mortgage adviser before you change how you overpay.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Thinking of trying Sprive?
The current sign-up offer, and the steps to claim it, stay up to date on my referral page.
Seven days of a higher rate, and no button to press
A Sprive boost is a promotional uplift on your cashback rate. It arrives on its own and runs for seven days. On my screen it added between half a point and a full point at the supermarkets. Supercharge is a separate switch and it pays you nothing extra. So when you see a big Sprive percentage quoted somewhere, work out which of the two it came from.
The short answer
A boost changes what you earn. Sprive lifts the cashback rate on the gift cards you buy inside the app. That extra money lands in your balance and goes to the mortgage. Supercharge only changes what the screen says. It adds your projected mortgage interest saving on top of the rate, so the percentage grows and your balance does not.
Both sit in the same place in the app, which is where the confusion starts. For the mechanics in general, read my guide to how Sprive cashback works. It covers the gift cards and which retailers repay the faff. This page is about the uplift on top of them.
What a Sprive boost actually is
A boost is a promotional rate, applied to your account for a short window. While it runs, the included brands in the Shop tab show a higher percentage. The gift card you buy then pays that higher percentage into your balance. It is real money rather than a projection, which is the whole difference between a boost and Supercharge.
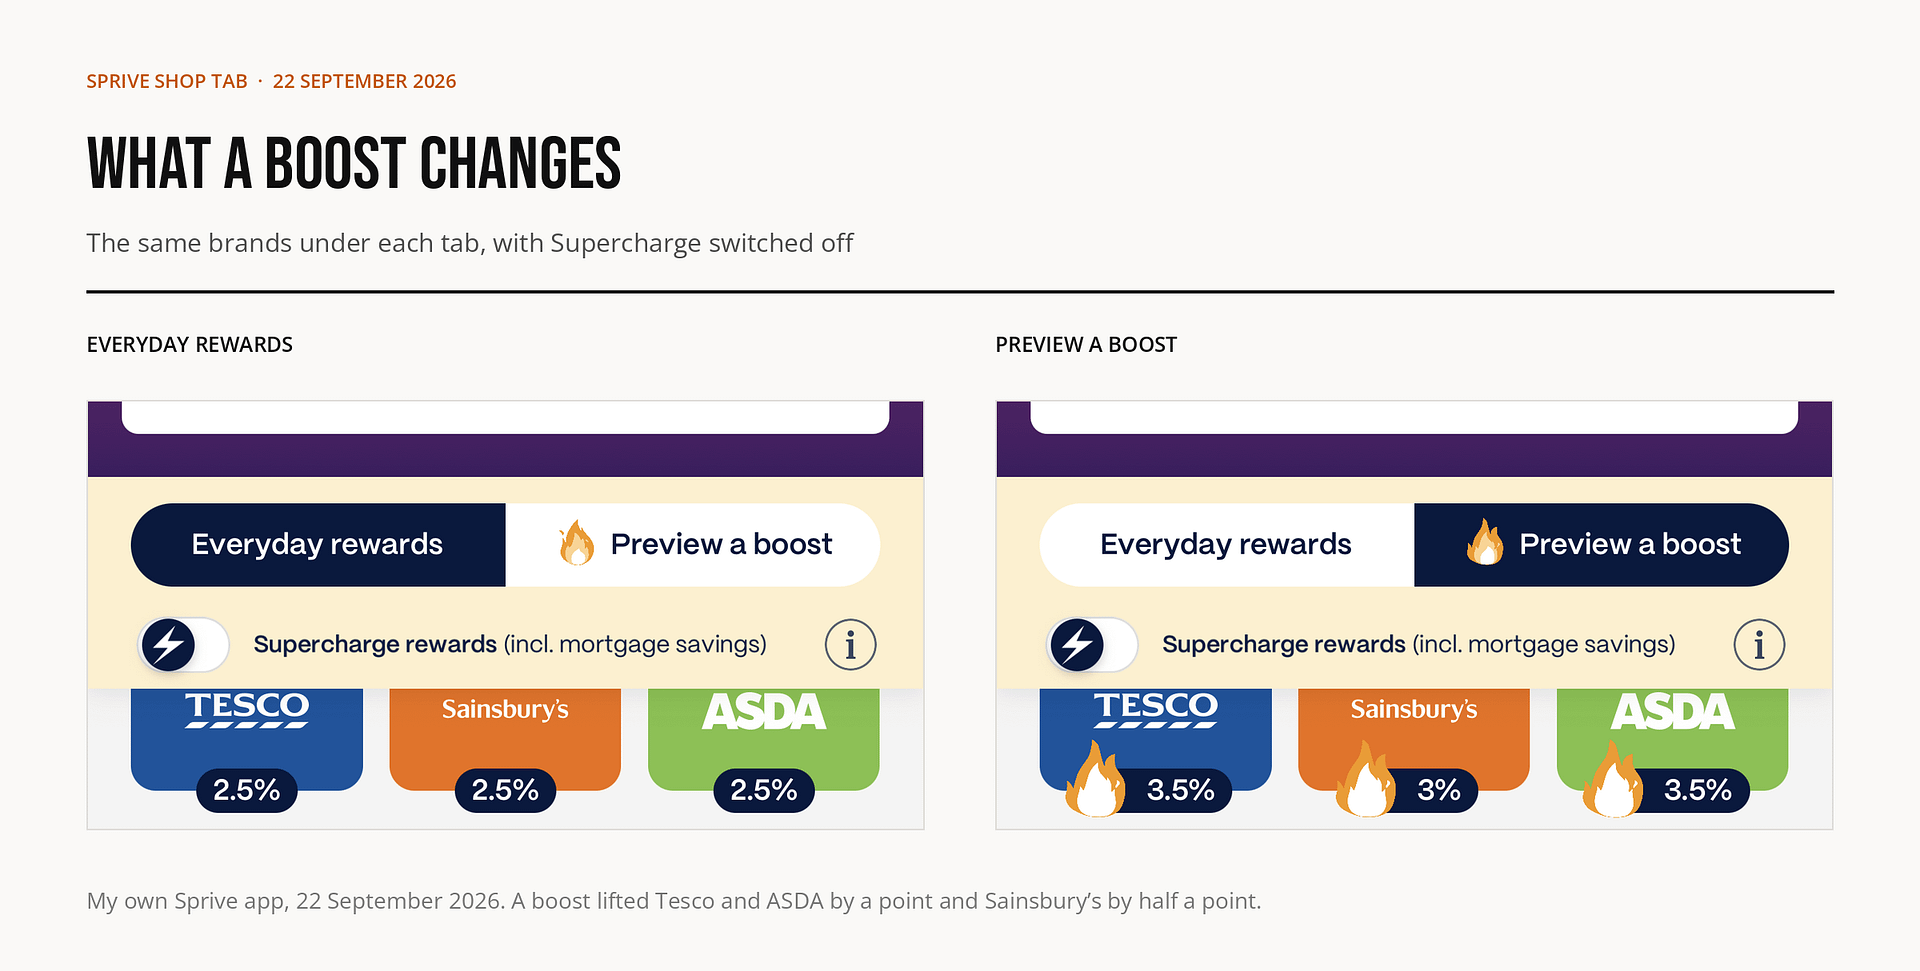
My own screen showed Tesco at 2.5% as standard and 3.5% under a boost. M&S moved the same way, 2.5% to 3.5%. Sainsbury's moved less, from 2.5% to 3%. The pattern held across the grocery brands in my app: half a point to a full point, no more. Ocado was the exception. It sat at up to 1.9% in both views, so a boost does not lift everything you buy.
The full grocery list, brand by brand, sits in my rundown of which supermarkets Sprive supports. Those rates move often, so your own app beats any table of mine.
Because it is a promotion, it also ends. A boost is not free money and it is not a rate you can budget around. It is a week of slightly better terms on shopping you were doing anyway. The moment it pushes you into buying something you did not need, the arithmetic has gone backwards.
Supercharge changes the number, not the money
Sprive labels this one honestly. The switch reads "Supercharge rewards (incl. mortgage savings)", and it sits directly under the two tabs. Turn it on and the app folds your projected mortgage interest saving into the percentage. You then get one combined figure for the total benefit of a purchase.
Supercharge therefore adds your mortgage savings prediction, and it does not give you any extra cashback. The forecast half depends on your rate, your balance and your remaining term. Change any of those and the figure moves with it. To see what you will actually earn this week, switch Supercharge off first and read the plain number.
Where to find both in the app
Open the Shop tab and look at the top of the screen. Sprive puts two tabs there, "Everyday rewards" and "Preview a boost", under a heading it calls "Instant-reward". The Supercharge switch sits on the row underneath, so it applies to whichever tab you are looking at.
"Preview a boost" is useful even with no boost running. It shows what the same brands would pay if one arrived. Sprive presents it as an illustration rather than a promise, though my own boosted rates have matched it.
The same shop, three ways
Take a £120 weekly shop at Tesco, which is roughly what mine costs. At the standard 2.5% that gift card pays £3.00 into my Sprive balance. Under a boost at 3.5% the same shop pays £4.20. The difference is £1.20.
Now switch Supercharge on. The app shows a much larger percentage against Tesco, because it has added the interest I avoid by overpaying. The cash arriving in the balance is still £4.20. One figure is money this week. The other is a forecast stretched across the life of the loan, so the two do not compare.
How a boost arrives, and how it does not
There is nothing to claim. Sprive applies a boost automatically and it runs for seven days. You do not get to choose when it lands. No button, no opt-in, no code. If you are hunting through the app for a way to switch one on, you can stop.
Two routes have put one on my account. The first was a reward for joining. The second came off the back of using the app. I bought at least £50 of gift cards through Sprive four weeks running, and then a boost turned up. That is one account's experience rather than a rule, though. Sprive does not publish the criteria anywhere. The threshold may therefore differ between accounts, and it may change whenever Sprive wants. Neither sprive.com nor its FAQ page described boosts at all when I last read them.
Which is also why chasing one is a bad idea. Buying gift cards you did not need spends real money for an uncertain 1%. Nobody has promised you the rate either. If the cashback is the reason for the purchase, the maths has already stopped working.
Seven days of an extra point on a £120 shop is about £1.20.
What a boost is worth across a year
Most quotes of a Sprive rate leave the seven-day window out, and the window decides the value. A week covers one weekly grocery shop, plus whatever else you happen to buy in those seven days. So a boost on a £120 Tesco shop is worth about £1.20 more than the same shop without one.
For context, that same shop at the standard 2.5% earns about £156 across a full year. A boost week adds its pound or so on top of that, and then the rate drops back. Sprive publishes nothing about how often boosts arrive, so I cannot tell you what they add up to annually. On my own account boosts have turned up more than once in nearly five years. That makes a boost a small bonus rather than a reason to choose the app.
Three other things hold the number down. Cashback only pays at participating brands. A boosted rate is worth nothing at the shops Sprive does not cover. The money lands in your Sprive balance for the mortgage, not in your current account. That is the point of the app, though it is not the same as cash in hand. Some routes are also slow. Ocado runs on tracking links rather than a gift card, and the app quotes an average of 105 days for that reward.
What the boost does not tell you
A percentage on a tile says nothing about who holds your money. Sprive Limited is an appointed representative on the FCA Register, firm reference number 919863, for mortgage services. Its principals are Connect IFA Ltd and New Leaf Distribution Limited, firm reference numbers 441505 and 460421.
Money sitting in your Sprive wallet is held by PrePay Technologies Limited, firm reference number 900010, as electronic money. Safeguarding is the protection that applies there, not the Financial Services Compensation Scheme, so it works differently from the cover on a bank account. Cashback you have already sent to the lender has left the wallet, which means the question only applies to money still sitting in the app.
Whether overpaying is the right home for the money is a separate question. MoneyHelper covers it in its guide on whether to pay off your mortgage early. Most lenders cap penalty-free overpayments at 10% of the balance a year. Clearing expensive debt, or holding three months of savings, usually comes first.
Frequently asked questions
What is a Sprive boost?
It is a promotional uplift on the cashback rate in Sprive's Shop tab. While it runs, the gift cards you buy in the app pay a higher percentage into your Sprive balance. That balance then goes to your mortgage.
What does Supercharge mean in Sprive?
Supercharge is a display switch, labelled "Supercharge rewards (incl. mortgage savings)". It adds your projected mortgage interest saving on top of the cashback rate. The app then shows one combined figure instead of the cashback alone.
Does Supercharge earn me more cashback?
No. It changes the number on the screen and nothing else. For the figure that matches what lands in your balance, switch Supercharge off.
How long does a Sprive boost last?
Seven days. After that your rates return to the standard ones in the "Everyday rewards" tab.
How do I get a boost on Sprive?
You do not, in the sense of claiming one. Sprive applies boosts automatically and does not publish what triggers them. Mine arrived twice. One came as a joining reward. The other followed four weeks of buying at least £50 of gift cards through the app. That is what happened on my account, so treat it as an observation rather than a method. Do not spend money you had not planned to spend in the hope of triggering one.
How much does a boost add?
Between half a point and a full point on the grocery brands in my app. Not every brand moves, though. Tesco went from 2.5% to 3.5% and Sainsbury's from 2.5% to 3%, while Ocado stayed put. Those rates are from my own app on 2 October 2026 and they change often.
Is Sprive cashback paid to me or to my mortgage?
It builds up in your Sprive balance. You then send it to your lender in the app whenever you choose. It is an overpayment rather than money back in your current account.
Is Sprive safe, and is my money protected?
Sprive Limited is an appointed representative for mortgage services, firm reference number 919863. Its principals are Connect IFA Ltd and New Leaf Distribution Limited, firm reference numbers 441505 and 460421. Money in the app's wallet sits with PrePay Technologies Limited, firm reference number 900010. PrePay safeguards it as electronic money, and the Financial Services Compensation Scheme does not cover it. My longer answer on the app's security is in is Sprive safe.
More from CoolCuration
- Mortgage overpayment UK: the rules, the 10% allowance and every overpayment guide on the site in one place.
- Mortgage overpayment calculator: see what an extra £50 a month takes off your term.
- Cashback on groceries: the other routes I use on a weekly shop, Sprive aside.
- Chip: where the emergency fund goes, which comes before any overpayment.
- Gifts for a new home: for the friend who has just signed up for one of these mortgages.
Rates, offers and terms change, and Sprive's change without notice. Everything above reflects my own app and Sprive's own pages as read on the date at the top of this article. This article is not financial advice and it takes no account of your circumstances. CoolCuration is not authorised by the Financial Conduct Authority, so consider speaking to a qualified mortgage adviser before you change how you overpay.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Your home may be repossessed if you do not keep up repayments on your mortgage.
What's trending
Recent posts
- What Is a Sprive Boost? Seven Days, and What It Actually Pays
 A Sprive boost lifts your cashback rate for seven days, and it arrives on its own. What mine paid, and why Supercharge is a display toggle rather than extra cashback.
- Best Gifts for Coffee Lovers 2026Gifts for coffee lovers who already own a grinder: nine UK picks from £11.53 to £239, plus three popular presents I would skip.
- Anish Kapoor at the Hayward Gallery Review: Is It Worth £22?Last updated: 2 October 2026 By Tristan · Arts, exhibitions and creative culture This is an opinion piece. Views expressed are the author's own and do not constitute professional advice. Cool Factor: 3/5 The Anish Kapoor Hayward Gallery show is his first solo exhibition there since 1998. It fills the whole building, both outdoor terraces… Read more: Anish Kapoor at the Hayward Gallery Review: Is It Worth £22?
No Comments.