Last updated: 7 October 2026
By Stiv · Design, technology and personal finance
This is an opinion piece. Views expressed are the author's own and do not constitute professional advice.
This article is for informational purposes only and does not constitute financial advice. Some features of Plum involve investing, which carries risk including the possible loss of capital. Always do your own research or consult a qualified financial adviser. CoolCuration is not authorised by the Financial Conduct Authority. This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Keen to give Plum a go?
Our Plum referral page shows any current new-user offer and walks through the sign-up, .
Cool Factor
★★★☆☆
3 out of 5 · Cool
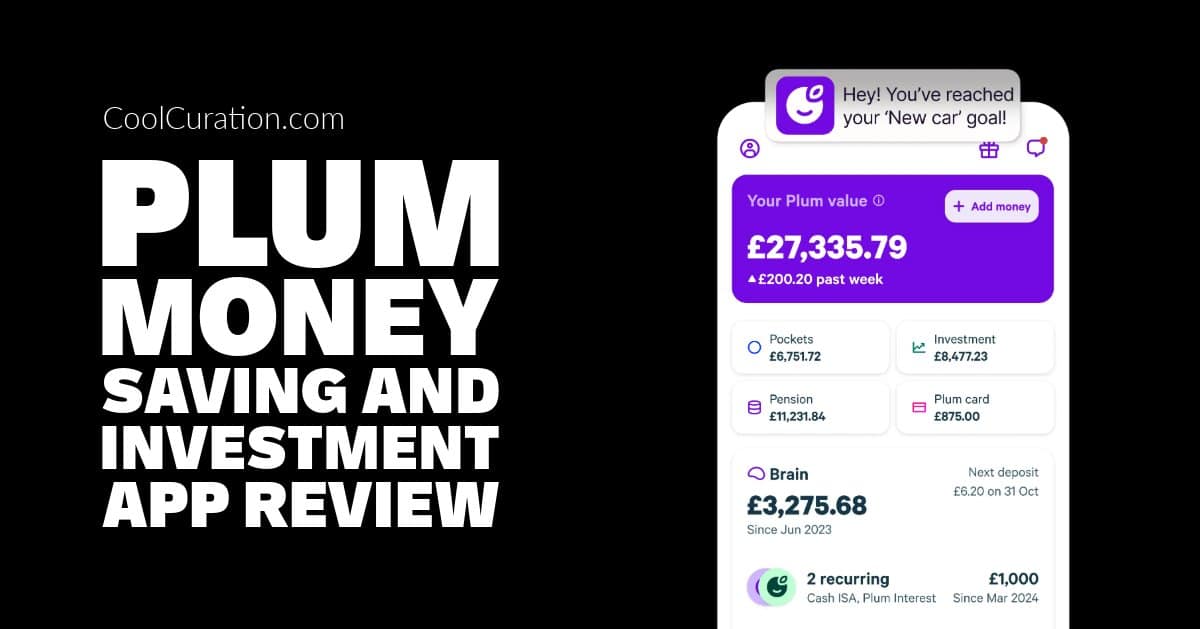
This Plum app review is based on three months of hands-on use. We set up Plum to run alongside our existing auto-saver to see whether it would earn a permanent place on our home screen. Plum is one of those apps that does a lot and wants you to know it. Auto-saving, round-ups, investing, bills management, cashback offers, interest-earning pockets. After three months of testing, here's whether all that activity translates into actually saving more money.
What Is the Plum App?
Plum is a UK fintech app that uses an algorithm to analyse your spending and automatically move affordable amounts into savings. On top of auto-saving, it offers round-ups, interest-earning pockets, investing (stocks, funds, and ISAs), a pension (SIPP), and bills management. It's available on iOS and Android, and has been downloaded by over two million people.
Plum Fintech Limited is registered with the Financial Conduct Authority (FRN: 836158), and its investment arm, Saveable Limited, is authorised and regulated by the FCA (FRN: 739214). You can verify both entries on the FCA Register.
First Impressions of the Plum App
Signing up took about five minutes. You download the app, enter your details, and connect your bank account via open banking. Plum only gets read-only access to your transactions, so it can't move money without your permission through a direct debit you set up.
The dashboard is where things get busy. There are tiles for saving, investing, pockets, cashback, bills, and a persistent nudge to upgrade to a paid plan. If you prefer apps that do one thing well and stay out of your way, Plum's visual density might feel like a lot at first. That said, once you find your way around, the layout is logical enough. It just takes a few sessions to settle in.
Setting up auto-saving was straightforward. You choose your "mood" (essentially how aggressively you want Plum to save), and within a few days the algorithm makes its first sweep from your bank account.
Auto-Saving: The Core of the Plum App Review
At the heart of this Plum app review is the auto-saving algorithm. Plum analyses your income and spending patterns and moves what it thinks you can afford. You control the intensity through mood settings ranging from "Shy" (very cautious) to "Beast Mode" (very aggressive).
Our experience: the default "Normal" setting was more aggressive than expected. In the first month, Plum moved about £180 without us doing anything. That was more than anticipated, and we had to dial it down to "Chilled". Once adjusted, it settled at about £120 to £140 per month, which felt right.
If you're living pay cheque to pay cheque, start on the lowest setting. You can always increase it once you're comfortable. Plum will never leave you overdrawn (it only saves what it calculates you can afford), but "can afford" is still a judgement call. The algorithm doesn't know about irregular expenses like car insurance renewals or birthday presents, so keep an eye on things during the first few weeks.
Auto-saving is available on all plans, including the free Basic tier. On the free plan you get six Auto Savers (rules that trigger saves), rising to ten on paid plans. For most people, six is plenty.
Round-Ups: Where Plum Shines
Every card transaction gets rounded up to the nearest pound, and the spare change is swept into savings. Plum calculates the total from the previous week's transactions and deposits the sum in one go, rather than after each individual purchase.
This is where Plum shines. The round-ups feel seamless. In our testing, they added about £30 to £40 per month. It's tiny amounts per transaction, but they compound into something meaningful over a few months. Over three months, round-ups alone contributed roughly £100 to our savings without any conscious effort.
Plum also offers "Pound-Ups", which deposit an extra £1 for transactions that are already whole numbers (like a £4.00 purchase). It's a nice touch if you want to accelerate things further. On top of those, there are gamified rules like the 52-Week Challenge (which builds savings week by week up to £1,378 in a year) and the Rainy Days rule (which saves a set amount whenever it rains in your area). They're fun additions, though we stuck with the core round-ups and auto-saves for simplicity.
Interest Rates and Savings Pockets
Plum offers several places to park your money, each with different rates and protections. Here's how they stood on Plum's own pages on 7 October 2026:
The Primary Pocket earns no interest. It's essentially a holding area for money before you move it into an interest-earning pocket or investment. Money here is safeguarded under e-money regulations but is not covered by the FSCS. Plum is moving this e-money from Modulr FS Limited to its own e-money firm, Plum Fintech Payments Limited (FRN 1023776), and new accounts open with Plum Fintech Payments from October 2026.
The Plum Easy Access Savings Account is Plum's new easy access product, provided by Lloyds Bank PLC. It pays 3.05% AER (variable) on the free Basic plan, 3.10% on Plus, 3.25% on Boost and 3.65% on Max (£14.99/month), with same-day access. Eligible deposits are protected up to £120,000 per eligible person per UK-authorised bank, building society or credit union by the FSCS (since 1 December 2025). Plum's older Easy Access Pockets are held with Investec Bank.
The Cash ISA pays 4.68% AER (variable) across all tiers, Plum's rate from 6 October 2026. However, that headline rate includes a 2.14% bonus that only applies for the first 12 months, and only if you meet Plum's conditions. After that, the rate drops to 2.54% AER. That's a big cliff, so factor it in before you commit. The money sits with a panel of banks, each covered by the FSCS up to £120,000 per person per bank.
The 95-Day Notice Pocket pays 3.87% AER but is only available on the Max plan. Also FSCS-protected via Investec Bank.
Plum Interest is a money market fund (BlackRock ICS Sterling Government Liquidity Fund) that tracks the Bank of England base rate. The projected yield ranges from 2.81% to 3.74% (variable) depending on your plan. This is an investment product, not a savings account. Your capital is at risk, and it is not covered by FSCS deposit protection. Eligible investments are protected up to £85,000 per person per FCA-authorised firm by the FSCS if the firm fails, but that does not cover falls in value.
The rates on the Easy Access Pockets are decent but not market-leading for a standard savings account. The Cash ISA headline rate is competitive at first glance, but always factor in that post-bonus drop. For a broader view of the best rates right now, see our best savings account UK guide.
If you already have savings with Lloyds, Investec, Citibank, QNB, BBVA or Nationwide (Virgin Money) (Plum's banking partners for different products), be aware that the £120,000 FSCS limit applies per banking licence, not per app. Check your combined exposure.
Investing with Plum
Plum offers investing within the app, including a Stocks and Shares ISA, General Investment Account, and a SIPP pension. You can invest in up to 3,000 US stocks and choose from up to 26 curated funds (depending on your plan tier). The funds are managed by providers like Vanguard and Legal and General, rebranded under Plum's own labels.
We haven't used Plum's investing features enough to review them properly. If you're looking at investing, we'd suggest dedicated platforms for greater control and lower fees. For a deeper look at your options, see our best investment ISA picks for 2026.
Capital at risk. The value of your investments can go down as well as up. You may get back less than you invest. Tax treatment depends on your individual circumstances and may change. This is not financial advice.
Free vs Paid: Is Upgrading Worth It?
Plum restructured its pricing in July 2025. The current tiers are:
Basic (free): auto-saving with 6 Auto Savers, Easy Access Savings at 3.05% AER, Cash ISA at 4.68% AER, Plum Interest at 2.81%, 1 customisable pocket, Stocks and Shares ISA, 2 free stock trades then £0.50 each, and a 0.60% management fee on investments.
Plus (£3.99/month): everything in Basic, plus 10 Auto Savers, 16 customisable pockets, 13 investment funds, lower trading fees (£0.15 per trade after 2 free), and a 0.45% management fee.
Boost (£7.99/month): everything in Plus, plus a Plum Visa debit card, Spend Insights, a better Easy Access rate (3.25% AER), 22 funds, trades at £0.05 each after 2 free, and a 0.30% management fee.
Max (£14.99/month): everything in Boost, plus the 95-Day Notice Pocket (3.87% AER), the top Easy Access rate (3.65% AER), 26 funds, unlimited free stock trades, a 0.15% management fee, lifestyle perks (travel insurance, cinema deals, NordVPN), and priority support.
We used the free Basic tier for the full three months. It did everything we needed for auto-saving and round-ups. The premium features are nice-to-haves, not must-haves. Unless you're actively investing through Plum or need the higher savings rates, the free tier is properly generous.
The Max plan at £14.99/month is steep. The lifestyle perks (2-for-1 cinema tickets, travel insurance, coffee discounts) are valued at £74/month according to Plum, but only if you'd actually use them. For most people, the free plan does the heavy lifting.
The App Itself
Plum's UX is colourful, feature-rich, and busy. There are a lot of tiles, menus, and options. For some users, that density is a strength: everything in one place. For others, it's clutter. We found ourselves wanting a simpler layout more often than not, though the app did grow on us as we learned where everything lived.
Reliability was generally good during our testing period. We didn't experience any crashes, and the auto-saving ran without issues. Notifications are manageable, and you can customise what Plum sends you. However, the upgrade prompts are persistent. Almost every section of the app includes a nudge to try Plus, Boost, or Max. It's not aggressive enough to be a dealbreaker, but it does get repetitive.
On 7 October 2026 the UK App Store listing rated Plum 4.7 out of 5 from about 71,000 ratings. The Cash ISA bonus is the detail to watch: the headline rate only lasts 12 months, so a reminder for when it drops is a good idea.
Value for Money
On the free tier, Plum is excellent value. You get a capable auto-saver, round-ups, an FSCS-protected Easy Access account at 3.05% AER, and a Cash ISA at 4.68% AER (for the first year). That's a lot for nothing.
The paid tiers are harder to justify unless you have a specific need. Plus (£3.99/month) makes sense if you want cheaper investing fees. Boost (£7.99/month) adds the debit card and better savings rates. Max (£14.99/month) is for power users who'll actually use the perks. If auto-saving and round-ups are your main goal, the free plan is all you need.
Plum features in our best money-saving apps roundup alongside several alternatives worth considering.
The Verdict
Cool Factor
★★★☆☆
3 out of 5 · Cool
Plum works. The auto-saving algorithm is effective, the round-ups are the best we've used, and the free tier is properly generous. But the app tries to do too much, the premium upsells are persistent, and the interface takes time to get comfortable with. It's a solid auto-saving app that earns its place on your phone, but it didn't quite blow us away.
If you'd like to try Plum, our link below opens the sign-up.
Try PlumWe also use Chip as our primary auto-saver. For a direct head-to-head, see our Sprive vs Plum vs Chip comparison.
Try Chip (£50 bonus)Overall, 3/5 Cool. This Plum app review confirms it does the job, and the round-ups are a real highlight. But it doesn't quite hit Stone cold because the app is cluttered, the premium nudges are annoying, and we found ourselves reaching for a simpler interface more often. If you want an everything-app for your finances, Plum delivers. If you want something quieter, there are cleaner alternatives.
For budgeting rather than auto-saving, see our Emma app review. And for the best savings rates right now, check our best savings account UK guide. You might also find our best savings options for the new tax year useful if you're planning ahead.
This article is for informational purposes only and does not constitute financial advice. Some features of Plum involve investing, which carries risk including the possible loss of capital. Always do your own research or consult a qualified financial adviser. CoolCuration is not authorised by the Financial Conduct Authority.
Plum App Review: FAQs
Is the Plum app safe in the UK?
Yes. Plum Fintech Limited is registered with the FCA (FRN: 836158), its e-money firm Plum Fintech Payments Limited is authorised by the FCA (FRN: 1023776), and its investment arm Saveable Limited is authorised and regulated by the FCA (FRN: 739214). Money in the Plum Easy Access Savings Account is held with Lloyds Bank, the 95-Day Notice Pocket with Investec Bank, and Cash ISA money with a panel of banks that Plum names as Citibank, Lloyds, Qatar National Bank, BBVA and Nationwide, each protected by the FSCS up to £120,000 per person per bank. However, money in the Primary Pocket is safeguarded under e-money regulations rather than FSCS-protected, and Plum Interest is an investment product where your capital is at risk.
How does Plum auto-saving work?
Plum connects to your bank account via open banking and analyses your income and spending patterns. It then calculates what you can afford to save and moves that amount via direct debit every few days. You choose your "mood" setting to control how aggressive the algorithm is, from "Shy" (very cautious) to "Beast Mode" (very aggressive). You can pause auto-saving at any time.
Is the Plum app free?
The Basic plan is free and includes auto-saving, round-ups, the Plum Easy Access Savings Account at 3.05% AER, and a Cash ISA at 4.68% AER. Paid plans start at £3.99/month (Plus) and go up to £14.99/month (Max), adding features like extra pockets, higher savings rates, cheaper investing fees, and lifestyle perks. The paid tiers are free for the first month.
Is my money protected in Plum?
It depends where your money sits. The Plum Easy Access Savings Account is held with Lloyds Bank, the older Easy Access Pockets and the 95-Day Notice Pocket with Investec Bank, and the Cash ISA with a panel of banks (Citibank, Lloyds, Qatar National Bank, BBVA and Nationwide, per Plum's money protections page on 7 October 2026). Each is protected by the FSCS up to £120,000 per person per banking licence. Your Primary Pocket balance is e-money, safeguarded by Plum Fintech Payments Limited but not FSCS-covered. If you also hold a Plum investment product, Plum says that cash counts as uninvested cash held with Saveable Limited instead. Plum Interest is an investment product (a money market fund) and your capital is at risk.
Can you withdraw money from Plum instantly?
Withdrawals from your Primary Pocket are near-instant (typically within 30 minutes), and Plum says the Plum Easy Access Savings Account pays out the same day. The 95-Day Notice Pocket requires 95 days' notice, as the name suggests. There are no withdrawal fees on the free plan, though the Cash ISA bonus only applies if you meet Plum's conditions for the full 12 months.
Is Plum regulated by the FCA?
Yes. Plum Fintech Limited is registered with the FCA as an Account Information Service Provider (FRN: 836158). Saveable Limited, which provides Plum's investment and ISA services, is authorised and regulated by the FCA (FRN: 739214). You can verify both on the FCA Register.
What interest rate does Plum pay?
Read on Plum's own site on 7 October 2026: the Plum Easy Access Savings Account pays 3.05% to 3.65% AER depending on your plan. The Cash ISA pays 4.68% AER (variable, Plum's rate from 6 October 2026), but that includes a 2.14% bonus that drops away after 12 months, leaving 2.54% AER. The Lifetime ISA pays 4.69% AER, including a 1.58% bonus, then 3.11% (Plum's rate from 28 September 2026). The 95-Day Notice Pocket pays 3.87% AER (Max plan only). Plum Interest (a money market fund, not a savings account) shows a variable yield of 2.81% to 3.74% depending on your plan, but your capital is at risk. All rates are variable and subject to change.
Does Plum have a Cash ISA?
Yes. Plum's Cash ISA is available on all plans, including the free Basic tier. The current rate is 4.68% AER (variable), though this includes a 12-month bonus rate of 2.14%. After 12 months, the rate drops to 2.54% AER. Transferring an existing ISA in earns 3.75% AER instead, including a 1.21% bonus. It's a flexible ISA, so you can withdraw and redeposit within the same tax year without using up your annual allowance. Deposits are FSCS-protected up to £120,000 per bank, held with a panel Plum names as Citibank, Lloyds, Qatar National Bank, BBVA and Nationwide (Virgin Money) rather than Investec.
More from CoolCuration
- Freetrade Review UK: a look at the commission-free investing app and how it stacks up.
- TopCashback Referral Code: earn a bonus when you sign up and start getting cashback on everyday spending.
- Oura Ring 4: a smart ring for tracking your health, sleep, and recovery.
- Airtime Rewards: earn cashback towards your mobile bill just by shopping at participating retailers.
- Exhale Coffee Review: our take on this UK speciality coffee roaster and whether it's worth subscribing.
- Gifts for Techies: our curated gift guide for gadget lovers and tech enthusiasts.
What's trending
Recent posts
- New on Mobbin October 2026: Jomo, Delphi, Lloyds and More
 New on Mobbin October 2026: Jomo, Delphi, Lloyds and five more apps, with the consent, search and unlock screens worth studying.
- British Art Fair 2026 ReviewArt fairsSaatchi Gallery A Sickert study best in show, a Hockney for £800, and naff AI art Last updated: 28 September 2026. I checked every price and date in this British Art Fair review against the dealers' labels and the fair's own pages. By Tristan · Arts, exhibitions and creative culture This is an opinion… Read more: British Art Fair 2026 Review
- Quentin James McCaffrey at Alison Jacques ReviewLast updated: 6 October 2026 By Tristan · Arts, exhibitions and creative culture This is an opinion piece. Views expressed are the author's own and do not constitute professional advice. Cool Factor: 3/5 Quentin James McCaffrey's first UK solo show was on at Alison Jacques from 3 September to 3 October 2026. Comprising fifteen small… Read more: Quentin James McCaffrey at Alison Jacques Review
No Comments.