Last updated: 18 October 2026. I checked every figure in this Sprive five years diary against my own Sprive app on 13 October 2026.
By Stiv · Design, technology and personal finance
I set Sprive up in October 2021 against my Nationwide mortgage. In June 2026 I remortgaged to Halifax and took the app with me. The figures below cover both mortgages.
Affiliate disclosure: This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
This is not financial advice. CoolCuration is not authorised by the Financial Conduct Authority, and I write here as a Sprive user rather than as an adviser. Check your own mortgage terms, and speak to a qualified mortgage adviser before you change how you overpay.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Thinking of trying Sprive?
The current sign-up offer, and the steps to claim it, stay up to date on my referral page.
How Sprive has helped me overpay my mortgage by £10,237.41
Five years of Sprive has put £10,237.41 into my mortgage on top of the normal monthly payments. Most of it came from the monthly auto-save rather than shopping cashback. Sprive's own dashboard now projects £71,000 of interest saved and nine years off the term, as long as I keep overpaying at my average.
New to the app? For setup, the cashback mechanics and every other Sprive guide in one place, see my Sprive guides hub.
October 2021
Where I started
A 1.66% five-year fix with Nationwide, and £100 a month on auto-save.
I took the Nationwide fix in the middle of the pandemic, when Bank Rate sat at 0.1%. Then, in October 2021, I set up Sprive and pointed a £100 monthly auto-save at that mortgage. The idea was simple. A fixed amount leaves my current account every month, sits in the app, and goes to the lender as an overpayment.
Amazon was in the Shop tab back then, and I used it a lot. So the plan from the start was the auto-save, plus whatever the shopping cashback added on top.
2022 and 2023
Rates went up, and my fix did not
Bank Rate went from 0.1% to 5.25%. My mortgage rate stayed at 1.66%.
The Bank of England raised Bank Rate for the first time on 16 December 2021, to 0.25%. It then rose 14 times in a row and reached 5.25% on 3 August 2023, according to the Bank of England's Bank Rate history. Meanwhile my payments did not move at all, because the fix held my rate at 1.66% until June 2026.
So the auto-save just kept running. It has gone out every single month since October 2021, without a pause or a skipped payment. The amount changed, though. I raised it to £500 a month for a stretch, and it sits at £250 a month now.
2024 and 2025
The cuts, and the end of the fix
Bank Rate fell from 5.25% to 3.75% as my Nationwide deal ran down.
The first cut came on 1 August 2024, to 5%. Five more followed, and by 18 December 2025 Bank Rate was down to 3.75%. That still left it more than twice my fixed rate. In other words, any new deal was going to cost more than 1.66%.
June 2026
Nationwide to Halifax
A new five-year fix at 3.97%, and the app moved across with it.
In June 2026 I remortgaged to Halifax on a five-year fix at 3.97%. That is a little under two and a half times the rate I had before. Switching Sprive over to pay off the new mortgage was pretty seamless, and the auto-save carried on.
Halifax is also changing. Lloyds Banking Group is folding the Halifax brand into Lloyds across 2026 and 2027, as Which? reported on 2 July 2026. Sprive's own FAQ lists both Halifax and Lloyds as supported lenders. My list of Sprive's supported lenders covers who else is on it.
Bank Rate has stayed at 3.75% since. The Bank of England held it on 17 September 2026, and its next decision is due on 5 November 2026.
The breakdown
What the cashback actually added
Most of the £10,237.41 is auto-save. Shopping cashback is a small slice of it.
I do not have an exact split from the app, so here is an estimate instead. I spend between £100 and £200 a month at the supermarkets, with auto top-ups switched on. At today's standard supermarket rate of about 2.5%, that earns roughly £2.50 to £5 a month. On top of that, I get a boost every four weeks, because I keep to the £50 gift card minimum. A Sprive boost adds about a point for seven days, so it brings in another 25p to 50p a month on my spending.
Taken together, that is something like £35 to £65 a year from groceries, if today's rates had applied throughout. Over five years of Sprive it comes to a few hundred pounds, or roughly 2% to 3% of the total. Bigger one-off purchases added more. I bought a printer at Currys through the app, the HP that later failed and that I wrote up in my HP Colour Laser 150nw review, plus heaters from Homebase and Currys. Referral credits from readers who signed up through my link on this site are in the total too. Even so, the auto-save carried most of the total. The current supermarket rates are on my Sprive supermarkets page.
The projection
The £71,000 figure, and what it is
Sprive's estimate if I keep going at my average, not money I have saved yet.
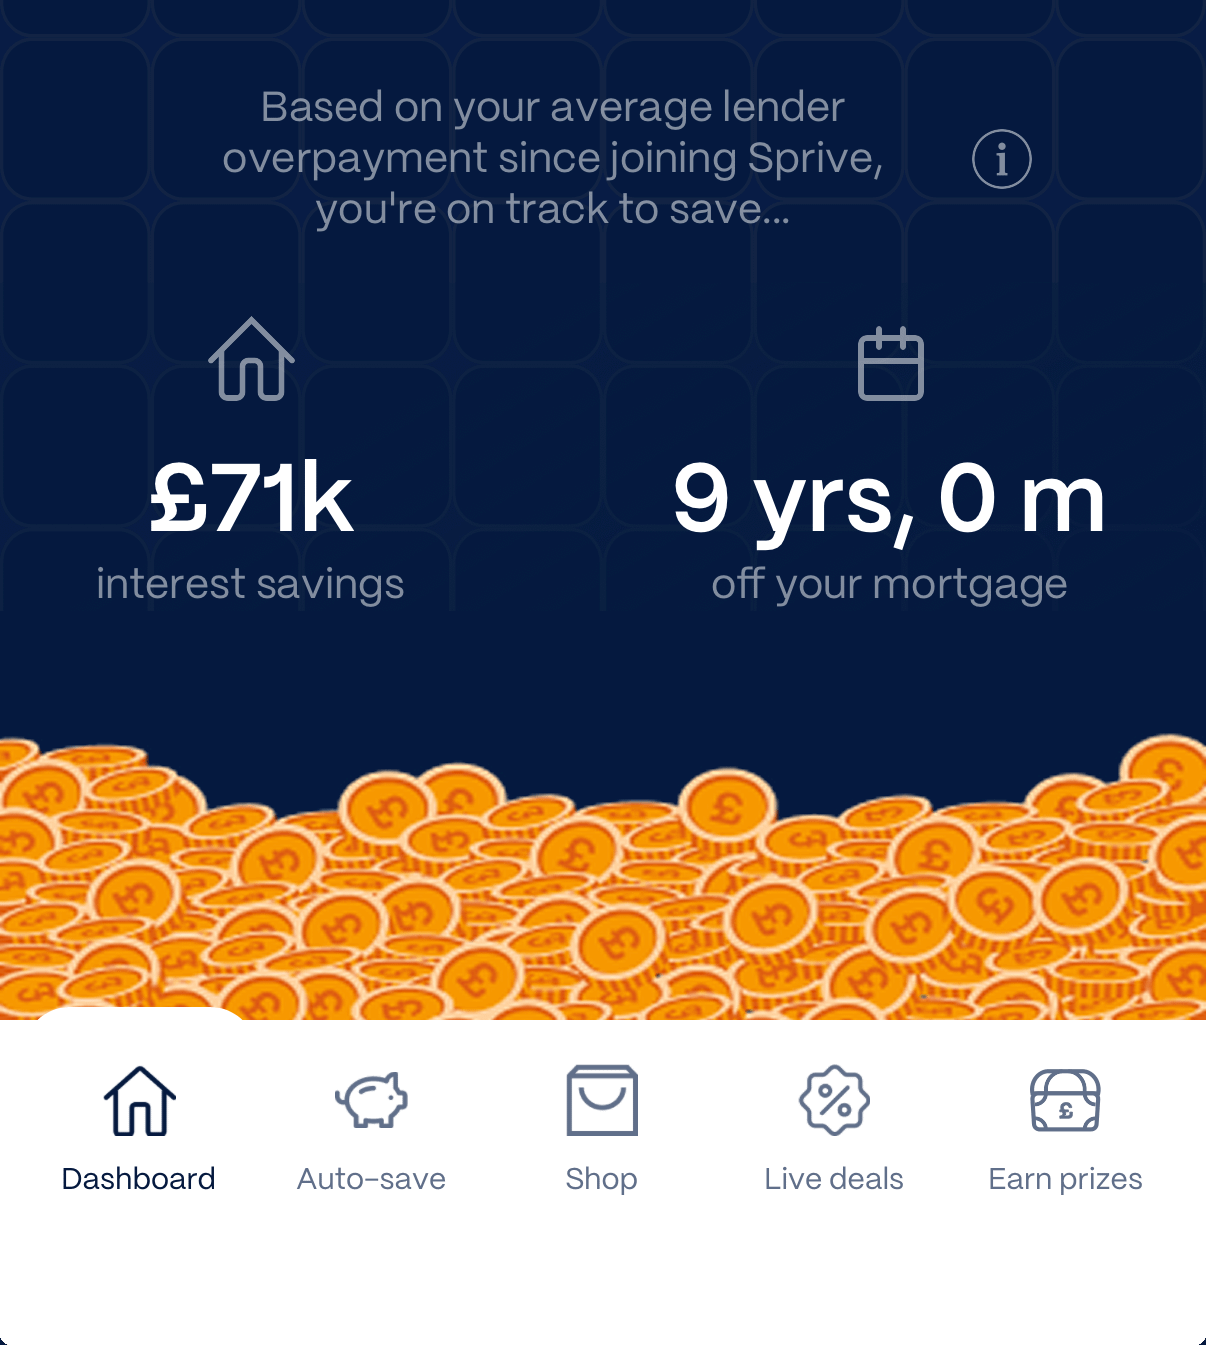
After five years of Sprive, the dashboard puts it like this: "Based on your average lender overpayment since joining Sprive, you're on track to save..." Underneath sit two numbers, £71k of interest savings and nine years off the mortgage. Both are projections over the full term. They assume I carry on overpaying at my average, so they will change if I stop, if I overpay more, or when my rate changes.
The money I can point to is the £10,237.41 already paid off the balance. The £71,000 is what that habit could be worth by the end of the term. If you want to see how an overpayment turns into interest saved, my mortgage overpayment savings guide runs the worked examples.
The other side
What has not worked in five years of Sprive
The cashback stayed small, Amazon went, and the big number is still a forecast.
The cashback is small on my spending. Around £100 to £200 a month of groceries earns a few pounds. That is useful, but it is not what pays a mortgage down.
Amazon left. It used to be in my Shop tab and I bought through it a lot. It is not there now, so those purchases no longer earn anything through Sprive.
Bank Rate sat above my fixed rate from August 2022. It rose to 1.75% that month and stayed above my 1.66% rate for the rest of the deal. During that time, every pound I overpaid saved 1.66% in interest. So any savings account paying more than 1.66% would have earned more on the same pound than overpaying saved. My guide to overpaying versus investing goes through that trade-off.
The big number is a forecast. The £71,000 and the nine years depend on me keeping the auto-save going, and on rates I cannot know yet.
The FSCS does not cover the wallet. Money waiting in the app sits with PrePay Technologies Limited as safeguarded electronic money. Once it reaches the lender it is part of the mortgage, but until then it is not deposit-protected.
Hindsight
What I would tell myself in 2021
Overpay little and often, and keep three to six months of cash aside first.
Paying off little bits more often does make a huge difference. I would balance the security of paying down a debt against the potential gains of investing, though. And I would always keep some aside in an easy access pot, so there is between three and six months of safety cash before anything goes to the mortgage. My guide to the best savings accounts compares the places to keep it.
Today
Sprive five years on: would I start again?
I am still using it, and the auto-save is higher now than when I started.
Five years into Sprive, the auto-save is at £250 a month, more than double the £100 I began with. When I remortgaged, I moved Sprive to the new lender rather than switching it off. So by what I have actually done, the answer is yes.
For my opinion of Sprive itself, the features and the downsides, read my Sprive mortgage app review. And if you are weighing the app against a plain standing order to your lender, I compare the two in Sprive vs manual overpaying. Both sit under my mortgage overpayment guide, which covers the rules and limits.
Sprive five years FAQs
How much have I overpaid with Sprive in five years?
£10,237.41 as at 13 October 2026, across a Nationwide mortgage and then a Halifax one. Most of it came from the monthly auto-save, with a small share from shopping cashback, boosts and referral credits.
Does Sprive keep working if you remortgage to a new lender?
It did for me. When I moved from Nationwide to Halifax in June 2026, I pointed the app at the new mortgage and the auto-save carried on. Your new lender has to be on Sprive's supported list for that to work, though.
How much of a Sprive total comes from cashback?
On my spending, very little. Groceries of £100 to £200 a month earn something like £35 to £65 a year at today's rates. Over five years that is roughly 2% to 3% of my total. Bigger one-off purchases add more.
Is the interest saving in the Sprive app real money?
No, it is a projection. Sprive bases it on your average overpayment since joining and runs it over the rest of the term. The figure changes if your overpayments or your rate change.
Is Sprive regulated, and is the money in the app protected?
Sprive Limited is an appointed representative of Connect IFA Ltd and New Leaf Distribution Limited for mortgage services, with firm reference number 919863 on the FCA Register. The principals' firm reference numbers are 441505 and 460421. Money in the app's wallet sits with PrePay Technologies Limited, firm reference number 900010, as safeguarded electronic money, and the Financial Services Compensation Scheme does not cover it.
More from CoolCuration
- When to remortgage: when to start looking for your next deal, and the standard variable rate trap.
- Mortgage overpayment calculator: put in your own balance and rate and see what an extra amount each month does.
- TopCashback referral code: cashback on online shopping, paid out as cash rather than to a mortgage.
- Airtime Rewards: cashback that comes off your phone bill rather than your mortgage.
- Gifts for homebodies: presents for people who would rather be at home.
Rates, offers and terms change, and Sprive's change without notice. Every figure above comes from my own app and accounts, and Sprive's own pages, as at 13 October 2026. This article is not financial advice and it takes no account of your circumstances. CoolCuration is not authorised by the Financial Conduct Authority, so consider speaking to a qualified mortgage adviser before you change how you overpay.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Your home may be repossessed if you do not keep up repayments on your mortgage.
What's trending
Recent posts
- Five Years of Sprive: What It Actually Did to My Mortgage
 Five years of Sprive on my own mortgage: £10,237.41 overpaid, a remortgage from Nationwide to Halifax, and what the cashback actually added.
- grug App Review UK: Daily Wisdom in Caveman SpeakOctober's App of the Month: grug, the free iPhone app where a caveman writes you one small piece of wisdom every morning, in lettering its makers drew by hand. Winner of Apple's 2026 Design Award for Delight and Fun. Cool Factor 4/5. @grug_app #grug #AppOfTheMonth #AppleDesignAwards #iPhoneApps #AppDesign
- Qobuz vs Spotify vs Apple Music: Which Should You Pay For?Last updated: 13 October 2026 By Stiv · Design, technology and personal finance Music streamingUK prices Which music streaming service should you pay for? Qobuz vs Spotify is the comparison most people land on once they start caring how their music sounds, and Apple Music sits right between the two. All three stream lossless audio… Read more: Qobuz vs Spotify vs Apple Music: Which Should You Pay For?
No Comments.