Last updated: 26 October 2026. I updated the fees, offers, app screenshots and my own returns in this JPMorgan Personal Investing review.
By Stiv · Design, technology and personal finance
This is an opinion piece. Views expressed are the author's own and do not constitute professional advice.
Cool Factor: 4/5
This JPMorgan Personal Investing review comes from years of my own money on the platform, starting back when it was still called Nutmeg. I hold eight managed pots there, including a Stocks and Shares ISA, a Lifetime ISA and a pension, all at the top risk level of 10 out of 10. Below is what the app is like day to day, what it costs and how my pots have done. I've also covered what changed when JPMorgan redesigned the app this autumn.
I was also a small backer in Nutmeg's Crowdcube raise before JPMorgan bought the business. That Enterprise Investment Scheme (EIS) holding returned roughly 50% when the sale went through. It has no bearing on how I rate the service today.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results.
Want the JPMorgan Personal Investing sign-up offer?
The latest new-customer offer, and how it compares with JPMorgan's own joining offer, is kept up to date on our referral page.
What is JPMorgan Personal Investing?
JPMorgan Personal Investing is the UK digital wealth manager owned by J.P. Morgan. It started life as Nutmeg in 2012, one of the UK's first robo-advisers, and JPMorgan bought it in 2021. The Nutmeg name was retired in November 2025, and every account, pot and portfolio carried straight across.
You choose an investment style and a risk level from 1 to 10. JPMorgan's in-house team then builds, runs and rebalances a global portfolio of exchange-traded funds (ETFs) for you. The products are a Stocks and Shares ISA, Lifetime ISA, Junior ISA, Personal Pension and General Investment Account. You can start from £500, or £100 for a Lifetime ISA or Junior ISA. The JPMorgan Personal Investing service guide lists every product rule in one place.
The company is authorised and regulated by the Financial Conduct Authority (FCA reference: 552016). Eligible investments are protected up to £85,000 per person per FCA-authorised firm by the FSCS. At the rebrand, JPMorgan said it looked after more than £8.5 billion for over 265,000 UK investors, up from £3.5 billion when it bought Nutmeg, according to FStech's launch report. Mark O'Donovan, who runs JPMorgan's international consumer bank, described the plan as "the ability to bank with Chase and invest with JPMorgan".
The new home screen

The app had a visual refresh this autumn, and the home screen is where you notice it. The top now shows one total for everything you hold, with your overall gain beside it. Underneath, your existing pots sit in their own Managed investments card, and below that is a new Self-Managed investments card with a blue "Coming soon" badge.
Tap that card and you can join a waitlist for picking your own investments, which I did. There are no fees, dates or details yet, just a row of company logos such as Apple, Nvidia and Microsoft, which suggests individual shares will be part of it.
The rest of the app works as it did before, which suits me fine. The one part of the refresh I don't love is the colour. Buttons such as Pay in are now a sharp, acidic green that clashes with the calm greys and the J.P. Morgan serif everywhere else.
Investment styles, and how I set up my pots
JPMorgan Personal Investing offers six styles. Fully Managed is the original. Smart Alpha adds active funds and research from J.P. Morgan Asset Management. Socially Responsible Investing (SRI) tilts towards companies with better environmental, social and governance scores. Thematic Investing bets on growth themes, Income Investing pays out a monthly income from £10,000, and Fixed Allocation keeps a set mix for a lower fee.
I tried Smart Alpha for six months. After that I moved everything into SRI at the highest risk level, so all eight of my pots now run the same style. Switching style takes a couple of taps on the pot, and changing the risk level is just as quick. Every so often JPMorgan Personal Investing asks me to review my answers to its risk questionnaire. It's a check that the level still suits me, and it takes a few minutes in the app.
Because I hold SRI pots myself, I've written a separate review of ESG investing with JPMorgan Personal Investing. It covers the MSCI scores, the top holdings and the awkward fact that JPMorgan Chase finances more fossil fuels than any other bank.
Paying in, and the Chase link

Paying in has always been easy here. You can use an easy bank transfer, which sends you to your banking app to approve the payment and gets the money invested in one to three business days. A debit card or Apple Pay takes three to five business days. You can also set up a monthly Direct Debit from any bank, which is what I use, and JPMorgan invests new money twice a week.
There's a useful safety net too. If your ISA hasn't been used yet this tax year, the app warns you before you pay in. Unless you reactivate the ISA first, which is a single tap, the money goes into a General Investment Account. Without that warning, a payment could quietly land outside the tax wrapper.
The fourth option is new: Pay in from your Chase app. You add JPMorgan Personal Investing as a payee in Chase and send money across like any other transfer.
Linking your Chase account

If you bank with Chase UK, you can also link the two accounts. Your pots then appear in the Invest tab of the Chase app, each with its value, gain and risk level. You can also open any pot to see its chart. It's nice to have, and if you'd rather not see it, you can unlink in the Chase app under Profile, Settings, Permissions and integrations.
In practice, though, it's only visibility. You can't change anything from Chase, and the JPMorgan Personal Investing app already shows the same numbers. I also track everything in one place with the Emma money app, which linked to Nutmeg long before Chase did, so the Chase link adds little for me.
Moving money between pots is the fiddly part

This is the one flow I still find annoying. To move money between pots, you first open the pot you want to take money from. Then you tap the menu in the top corner, choose "Transfer between pots" and pick the pot you're sending to.
Nothing on the home screen or the pot list points you there, and I regularly get the "from" and "into" pots muddled. In Chase, by comparison, you can swap the from and to accounts on the same screen. Transfers are free, but they only work between pots of the same type, so ISA to ISA or General Investment Account to General Investment Account.
The wealth planner and the human help

The app has a wealth planner, still marked beta. Mine shows a single cash reserve goal with a projected value and a target, plus a button to review the plan. In the app it's so bare that I don't see much point in it yet. The website version does more, but because I use Emma I don't need another place to track my money.
The human side is better. JPMorgan Personal Investing offered me a call with its wealth team to review the plan. I didn't take it up, but free guidance calls are open to anyone, with no minimum balance. That's rare at this price, and it's worth using if you are new to investing or have just come into some money.
What you'll pay: fees explained
Every pot carries three charges, all shown on JPMorgan's fees page. They are the annual management fee, the cost of the funds in the portfolio, and the market spread when JPMorgan buys and sells.
| Style | Management fee | Fund costs | Market spread |
|---|---|---|---|
| Fully Managed | 0.75% on the first £100,000, 0.35% above | 0.18% | 0.04% |
| Socially Responsible Investing | 0.75% on the first £100,000, 0.35% above | 0.23% | 0.04% |
| Smart Alpha | 0.75% on the first £100,000, 0.35% above | 0.34% | 0.04% |
| Thematic Investing | 0.75% on the first £100,000, 0.35% above | 0.25% | 0.04% |
| Income Investing | 0.75% on the first £100,000, 0.35% above | 0.39% | 0.04% |
| Fixed Allocation | 0.45% on the first £100,000, 0.25% above | 0.14% | 0.04% |
The £100,000 band works across pots. According to JPMorgan's fee help article, all your Fully Managed, Smart Alpha, SRI, Thematic and Income pots are added together. So £60,000 in one style and £60,000 in another pays 0.75% on the first £100,000 and 0.35% on the last £20,000. Fixed Allocation pots are counted separately. There are no set-up, exit or trading fees, and cash-only pots carry no fee.
What a typical pot costs a year
So what does that add up to? On £50,000 in SRI, the management fee is £375 a year, the funds cost another £115 and the spread about £20. That's roughly £510 a year, or just over 1% of the pot. Compared with picking ETFs yourself on a DIY app, that's a lot. The question is whether you'd invest at all, and stick with it, without someone doing it for you. Tax treatment depends on your individual circumstances and may change in future.
Any cash sitting inside an investment pot earns the Bank of England base rate minus 0.75%. New customers can also get a joining offer: the current one, and how it compares with the referral reward, is on our JPMorgan Personal Investing referral page.
My own pots: how they've performed

All eight of my pots run at the maximum risk level and in growth portfolios, so they swing harder than a cautious set-up in both directions. Across the whole account, the app shows me up 64.03% on the money I've paid in, as of 26 October 2026.
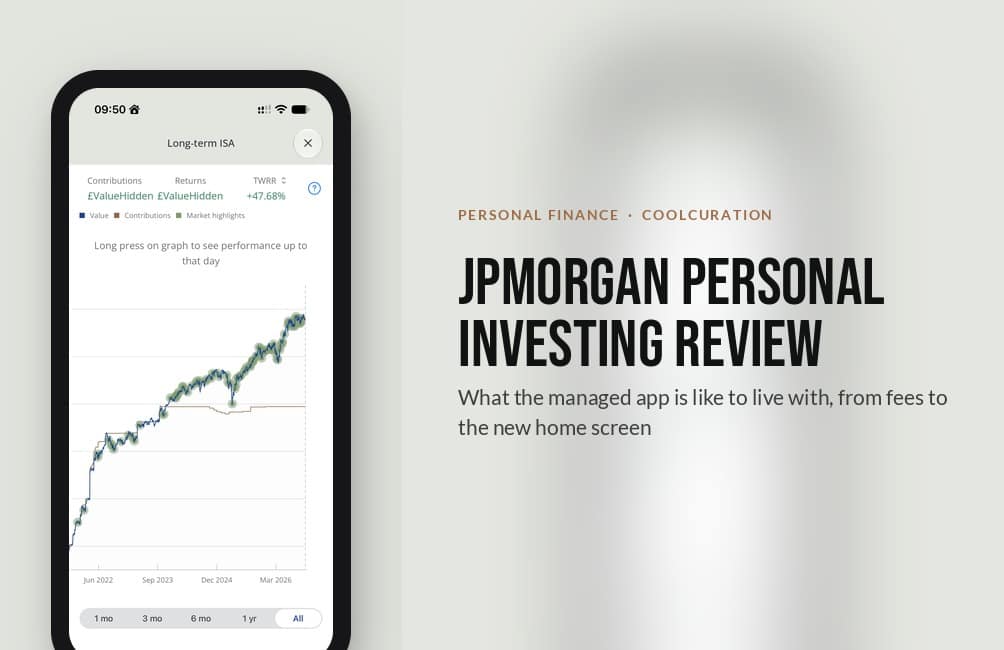
My main ISA pot is up 47.68% on a time-weighted basis. Its simple return, the plain gain against what I put in, is an estimated 52% or so. A newer pot I started in 2024 is up 37.81% time-weighted, and around 23% on a simple basis. My Lifetime ISA, opened in 2019, is up 53.96%. My pension, running since May 2019, is up 105.45%. Both of those are time-weighted figures too.
These figures will have moved by the time you read this. Past performance is not a reliable indicator of future results, and a maximum-risk, all-growth mix like mine can fall sharply in a bad year. You could get back less than you put in.
Time-weighted and simple returns

The app shows two kinds of return, and they measure different things. A simple return is the money gain: what the pot is worth now against what you paid in. A time-weighted rate of return (TWRR) strips out the timing of your payments, so it shows how the investments themselves performed.
Because I pay in by Direct Debit rather than in one lump, my two numbers drift apart. The pot chart plots value against contributions, and green dots mark market events. So a dip like the one in spring 2025 lines up with the news that caused it.
A note on the pension
JPMorgan chooses and manages the investments in the pension, but the pension itself is run by Embark Services Limited, with Embark Trustees Limited as trustee. The assets are held by State Street and Barclays, according to JPMorgan's pension page. That's normal for a pension of this kind, and it means the wrapper sits with a specialist administrator.
Tax time with a General Investment Account
If you hold a General Investment Account, JPMorgan sends a yearly tax pack with a consolidated tax certificate. It lists the dividends, interest, excess reportable income and capital gains or losses from your pots for the full tax year. That puts the figures for a Self Assessment return in one PDF.
I hand mine straight to my accountant through Taxfix, who works out what I owe. ISAs and pensions don't need any of this, because their returns are tax-free and aren't reported. JPMorgan explains each section of the certificate in its tax reporting guide.
Self-managed investing is on the way
The biggest gap on the platform so far has been the lack of DIY investing. That should change. When it rebranded in November 2025, JPMorgan said a full DIY platform for your own shares, bonds and funds would follow in 2026. The new Self-Managed card with its waitlist is the first sign of it in the app. I've rounded up what we know so far about JPMorgan self-managed investing, and I'll update it as details land.
There are no prices yet, so it's impossible to say how it will compare with the apps I use for my own share picks. I'll be watching three things: the dealing fee, the foreign exchange fee on US shares, and whether it works inside the same ISA as my managed pots. If you want a DIY app before JPMorgan Personal Investing launches its own, my Freetrade review, Lightyear review and Trading 212 review cover the main options.
Honest critical observations
No platform is perfect, and here's where JPMorgan Personal Investing falls short for me.
No DIY investing yet. Until the self-managed service launches, you can't pick your own shares or funds here. If that matters to you now, you'll need a second app.
The ISA isn't flexible. Take money out and it still counts against your yearly ISA allowance. Some rivals let you put withdrawals back in the same tax year without losing allowance.
The fees are on the high side. Just over 1% a year all in on an SRI pot is noticeably more than a DIY index approach. The lower 0.35% band only starts at £100,000, so most people pay the full 0.75%.
Transfers between pots are hidden. The flow sits behind a menu inside each pot, and the from and into choices are easy to mix up.
The in-app wealth planner is thin. One goal, a projection and a button isn't a plan yet, and it's still in beta.
Smaller niggles. Secure messages still push me towards the website, and I have 176 unread that I'm never going to open. The Insights tab, with its monthly investor updates and podcasts, is dry and technical for my taste, although I can see why some people would value it. And the new acidic green doesn't suit the rest of the design.
Value for money
It depends on what you want. If you'd like someone else to run your investments well, with a clear app, honest reporting and free access to a wealth team, JPMorgan Personal Investing delivers. You pay more than on a DIY app, and in return a team handles the choosing, rebalancing and risk.
If you're confident picking your own funds, a DIY platform will cost far less. If you want to compare the whole done-for-you market first, I ranked seven UK options on their full yearly cost in best managed investment platforms UK. In that review, JPMorgan Personal Investing came first on service, not on price. And if you're just starting out, my guide to how to start investing in the UK covers ISAs, pensions and risk first.
JPMorgan also publishes its full managed-portfolio history on its track record page. That lets you review the JPMorgan Personal Investing numbers yourself rather than take my word for it.
I've been here since the Nutmeg days, and it's still one of the few finance apps I actually enjoy opening.
JPMorgan Personal Investing review: the verdict
JPMorgan Personal Investing does what it promises. The styles are well chosen, the app is clear, paying in is very easy, and the fees are set out in full. The redesign hasn't broken anything, and the self-managed waitlist suggests the biggest gap is about to close.
It isn't the cheapest way to invest, and you hand the decisions over rather than make them. But for hands-off investors who want their money run by a regulated, well-known firm, it's one of the strongest managed options in the UK in my experience.
Cool Factor
★★★★☆
4 out of 5
All told, a solid 4/5 Stone cold. This JPMorgan Personal Investing review keeps the score it had in June. The app, the easy paying in, the clear fees and the free guidance calls earn it, along with years of steady growth in my own pots. It stops short of Ice cold because you still can't pick your own investments and the ISA isn't flexible. Moving money between pots is clumsy too, and the fees add up on larger pots. If the self-managed service launches with fair prices, that score could go up.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. This is my opinion and not financial advice.
Frequently asked questions
Is JPMorgan Personal Investing worth it?
For hands-off investors, I think so. My JPMorgan Personal Investing review gives it 4 out of 5 (Stone cold) for its clear app, easy paying in, transparent fees and free guidance calls. It loses a point because there's no DIY investing yet, the ISA isn't flexible and the fees are higher than picking your own funds.
Is JPMorgan Personal Investing the same as Nutmeg?
Yes. Nutmeg became JPMorgan Personal Investing in November 2025. The products, investment team and portfolios are the same, and existing Nutmeg accounts moved across automatically.
How much does JPMorgan Personal Investing cost?
The management fee is 0.75% a year on the first £100,000 for the managed styles and 0.35% above that, with all those pots added together. Fixed Allocation costs 0.45% and then 0.25%. Fund costs of 0.14% to 0.39% and a market spread of about 0.04% come on top. There are no set-up, exit or trading fees.
Can I buy individual shares on JPMorgan Personal Investing?
Not yet. The app now shows a Self-Managed investments section marked "Coming soon", with a waitlist. JPMorgan hasn't announced fees or a launch date. Until then, a DIY app such as Freetrade is the way to pick your own shares.
Can I link JPMorgan Personal Investing to my Chase account?
Yes. Once linked, your pots appear in the Invest tab of the Chase app, and you can pay in from Chase by adding JPMorgan Personal Investing as a payee. You can unlink at any time in the Chase app's Permissions and integrations settings, and your investment account stays open.
How do I move money between pots?
Open the pot you want to move money from, tap the menu in the top corner and choose "Transfer between pots". Then pick the pot you're sending to and the amount. Transfers are free, but only between pots of the same type, such as ISA to ISA.
What do time-weighted and simple returns mean?
A simple return compares your pot's value with what you paid in. A time-weighted rate of return removes the effect of when you added or took out money, so it shows how the investments themselves did. Neither is a forecast.
Is JPMorgan Personal Investing safe?
It's authorised and regulated by the Financial Conduct Authority (FCA reference: 552016), and your investments are held separately from the company's own money. If the firm failed, eligible investments are protected up to £85,000 per person per FCA-authorised firm by the FSCS. Your capital is still at risk from the markets.
Does JPMorgan Personal Investing have a referral offer?
Yes. JPMorgan runs a referral reward alongside its own joining offer, and you can only claim one. Our JPMorgan Personal Investing referral page has the latest offer and shows which one is worth more for the amount you plan to invest.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results. Rates, fees, offers and terms can change. This JPMorgan Personal Investing review is for information only and does not constitute financial advice. CoolCuration is not authorised by the FCA. Tax treatment depends on the individual circumstances of each client and may be subject to change in future. ISA and pension eligibility rules apply. Do your own research or consider a qualified financial adviser before making investment decisions. This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
More from CoolCuration
- Best investment ISA 2026: where to use your £20,000 allowance this tax year.
- Stock Events app: track holdings and dividends from every platform in one place.
- Chase refer a friend code: the current reward for opening a Chase UK account.
- Finimize app: short daily briefings on markets and investing.
- Gifts for techies: gadgets and tools for the person who reads every spec sheet.
What's trending

Recent posts
- JPMorgan Self-Managed Investing: What We Know So Far
 JPMorgan Personal Investing has added a Self-Managed investments waitlist to its app. What JPMorgan has said, what the app shows, and the open questions on fees and ISAs.
- New on Mobbin November 2026: Doji, Trainline, Tally and MoreNew on Mobbin November 2026: Doji, Trainline, Tally and five more apps, with the AI, pricing and privacy screens worth studying.
- Counter Editions Women in Print: Eight Limited Edition Prints with TateCounter Editions and Tate launch Women in Print on 10 November: eight limited edition prints by Tracey Emin, Katherine Bradford, Ulala Imai, Sophie von Hellermann and four more, with one third of the profits going to Tate.


No Comments.