Four Premium Bonds alternatives open to new savers, with each provider's published odds, prize tables, access rules and protection.
September 17, 2026Comments are off for this post.
Bank of England Base Rate: Where It Stands and What It Means
The Bank of England base rate is 3.75% after a 6 to 3 vote on 17 September 2026. What the hold means for mortgages, savings and energy bills.
April 29, 2026Comments are off for this post.
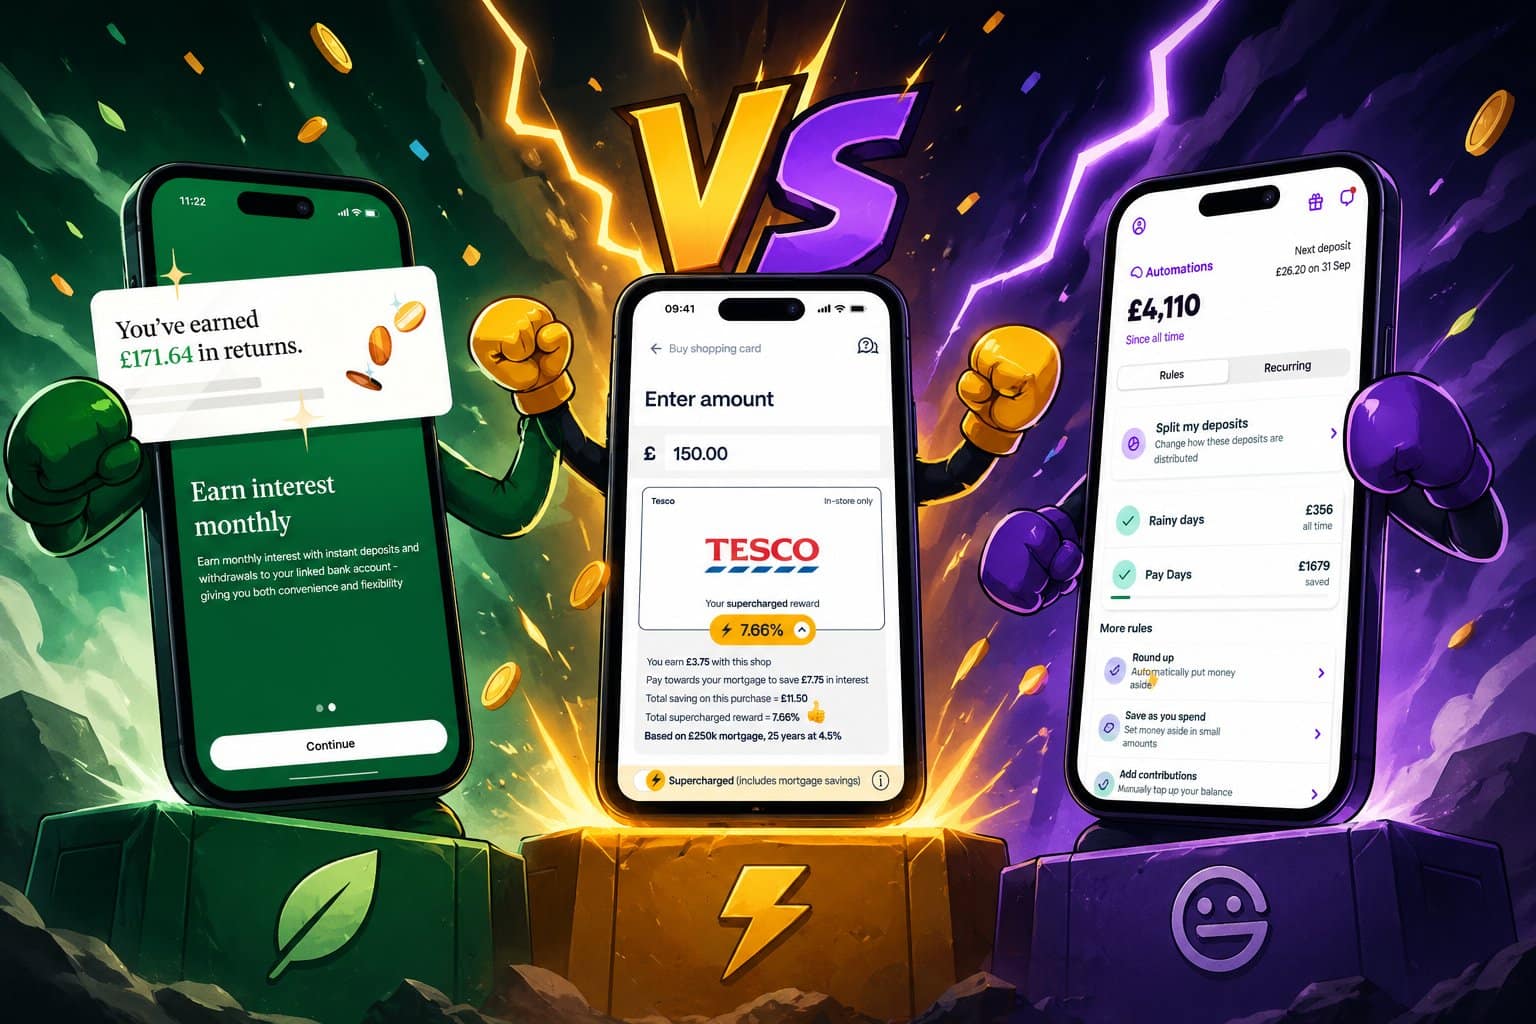
Sprive vs Plum vs Chip: Honest Comparison (2026)
Last updated: 10 September 2026
By Stiv · Design, technology and personal finance
I've been using Sprive with my Nationwide mortgage since October 2021, making £100 monthly overpayments through the app. This comparison is based on over four years of real use alongside Chip and Plum.
Sprive vs Plum vs Chip is the question that keeps coming up whenever anyone in the UK talks about saving money automatically. All three apps promise to do the hard bit for you. But they are not the same thing, and picking the wrong one means you are either missing features you need or paying for ones you do not. Here is how they actually compare after months of using all three.
Between the team, we run all three. Sprive handles mortgage overpayments. Chip is our primary auto-saver. Plum runs alongside Chip so we can see how the two compare in real life. Each has earned its place on someone's home screen, but for very different reasons.
This article is for informational purposes only and does not constitute financial advice. Some apps in this comparison offer investing features, which carry risk including the possible loss of capital. Your home may be repossessed if you do not keep up repayments on your mortgage. CoolCuration is not authorised by the Financial Conduct Authority. This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
Sprive's current sign-up offer
If Sprive ends up being your pick of the three, the latest welcome bonus is always on our referral page.
Comparing money apps? The three-way verdict is below. For everything we have written on Sprive in one place, see our Sprive guides hub.
Read more
April 18, 2026Comments are off for this post.
Best Savings Options for the New Tax Year UK 2026/27
Last updated: 10 September 2026
By Stiv · Design, technology and personal finance
Every April, we go through the same routine. The ISA allowance resets, savings rates shift, and there is a brief window where everyone actually pays attention to where their money is sitting. The best savings options for the new tax year are worth sorting now, before the motivation fades and another 12 months slip by. Here is what the CoolCuration team is doing with ours this year, along with a look at the platforms and accounts worth considering right now.
This year there is an added urgency. The 2026/27 tax year is the last year under-65s can put the full £20,000 into a cash ISA. From April 2027, cash ISA contributions will be capped at £12,000 for anyone under 65, with the remaining £8,000 needing to go into stocks and shares or other ISA types. So if you have been meaning to top up your cash ISA, this is the final window at the current limit.
Important: this is not financial advice. This article is for informational purposes only. Nothing in this post constitutes a recommendation to open any particular account, invest in any product, or take any specific financial action. Savings rates, ISA rules, and tax treatment can change at any time. CoolCuration is not authorised or regulated by the Financial Conduct Authority and cannot advise you on what is right for your circumstances. Always do your own research or speak to a qualified, independent financial adviser before making financial decisions. This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
Read more
April 11, 2026Comments are off for this post.
Chip Prize Saver vs Premium Bonds UK 2026: Which Is Actually Better?
Last updated: 10 September 2026
By Stiv · Design, technology and personal finance
Over 22 million people in the UK hold Premium Bonds, which makes them the nation's most popular savings product. Yet most holders have never weighed up Chip Prize Saver vs Premium Bonds side by side, and the numbers reward a closer look. Around 62% of Premium Bonds holders have never won a single prize, according to AJ Bell. The prize fund rate sits at 4.35% from the September 2026 draw, with each £1 bond facing odds of 21,000 to 1. NS&I has moved both twice this year. The rate ran at 3.30% with odds of 23,000 to 1 from April, went to 3.80% and 22,000 to 1 in July, then landed where it is now when NS&I announced the change on 18 August 2026.
Meanwhile, Chip's Prize Savings Account offers an alternative: a prize-draw savings account with a £10,000 grand prize every month and no interest at all. Both are a gamble on the return, not on the capital. You can hold either for a year, win nothing, and watch inflation eat the value of the money. We are not saying Premium Bonds are bad. Indeed, they are backed by the Treasury and pay tax-free prizes, which is a real advantage. However, if you have not compared them to anything in years, this is worth ten minutes of your time.
This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
Want to try the Chip Prize Saver?
Our Chip referral page carries the current new-customer bonus and the sign-up steps, kept up to date.
This article is for informational purposes only and does not constitute financial advice. It is not a recommendation to open, close, or switch any savings or investment product. Always do your own research or consider a qualified financial adviser before making financial decisions. CoolCuration is not authorised by the Financial Conduct Authority. Tax treatment depends on individual circumstances and may change. All product details were verified at the time of writing but may change, so always check the provider's website for current terms.
Read more
April 1, 2026Comments are off for this post.
Best Mortgage Overpayment Apps UK: Tested and Compared (2026)
Last updated: 17 September 2026
By Stiv · Design, technology and personal finance
I have a Nationwide mortgage and have been testing mortgage overpayment tools since 2021, including Sprive alongside manual standing orders and savings apps.
Disclosure: This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
Not financial advice. CoolCuration is not authorised by the Financial Conduct Authority. This article is for information only. Your home may be repossessed if you do not keep up repayments on your mortgage.
After the Sprive bonus?
Sprive leads the comparison below, and the sign-up offer it currently runs is covered on our referral page.
Looking for the best mortgage overpayment apps in the UK? Whether you want an app that automates everything, a savings tool that builds your overpayment pot, or a budgeting app that finds spare cash you didn't know you had, there are more options in 2026 than ever. I've tested and compared the main contenders so you can find the right one for how you actually manage money.
Read moreFollow us: Instagram
Copyright 2026 CoolCuration | Privacy Policy | Cookie Policy | Affiliate Disclosure | Cool Factor
-----------
We are proud supporters of a safer more private internet via encouraging people to use Brave browser and are actively taking on Spammers as part of ProjectHoneypot. This site is hosted on servers that run on 100% renewable energy in the UK thanks to GreenWebHosting.
This site contains affiliate links, including to Amazon.com and Amazon.co.uk. We may earn a commission if you make a purchase or sign up for a service via these links, at no extra cost to you. All offers and promotions are accurate at the time of publication but are subject to change or withdrawal by the businesses featured. We cannot guarantee their continued availability. Read our full affiliate disclosure.
Reviews and opinions on CoolCuration reflect the personal experience of our writers at the time of publication. They are not professional endorsements and your experience may differ. Scores use our Cool Factor rating system and are given independently of any commercial relationship.
All content on CoolCuration is provided for informational and entertainment purposes only. It does not constitute financial advice, investment recommendations or an endorsement of any product or service. We are not authorised by the Financial Conduct Authority and do not offer personalised financial guidance. You should always do your own research or consult a qualified financial advisor before making any financial decisions.