The Bank of England base rate is 3.75% after a 6 to 3 vote on 17 September 2026. What the hold means for mortgages, savings and energy bills.
September 2, 2026Comments are off for this post.
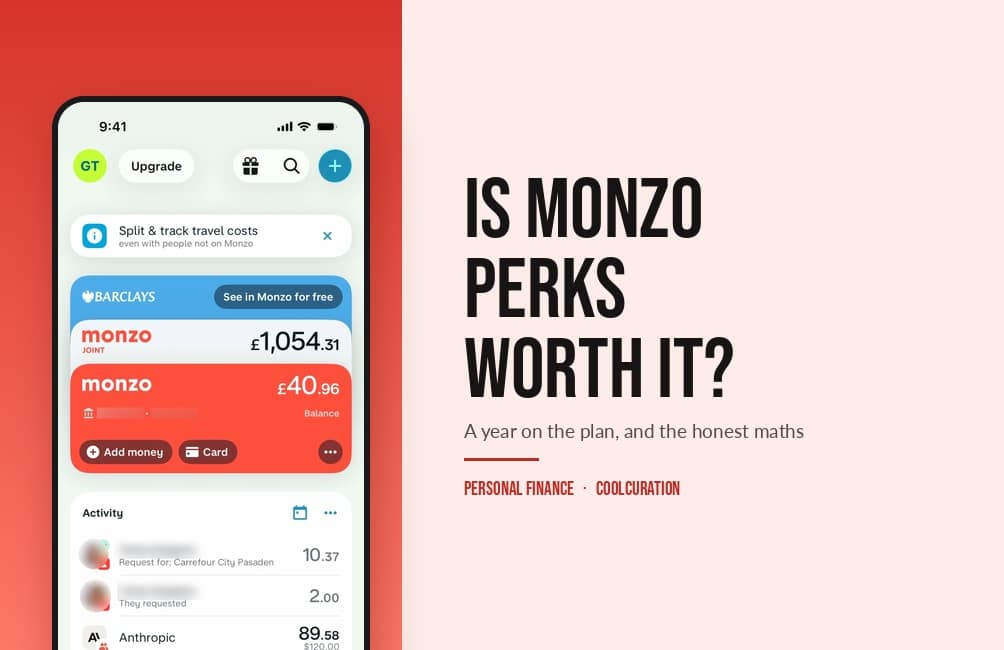
Is Monzo Perks Worth It? A Year of Paying for It
A year of paying £9 a month for Monzo Perks, with the honest maths on what I actually claim and what earns nothing.
April 18, 2026Comments are off for this post.
Best Savings Options for the New Tax Year UK 2026/27
Last updated: 10 September 2026
By Stiv · Design, technology and personal finance
Every April, we go through the same routine. The ISA allowance resets, savings rates shift, and there is a brief window where everyone actually pays attention to where their money is sitting. The best savings options for the new tax year are worth sorting now, before the motivation fades and another 12 months slip by. Here is what the CoolCuration team is doing with ours this year, along with a look at the platforms and accounts worth considering right now.
This year there is an added urgency. The 2026/27 tax year is the last year under-65s can put the full £20,000 into a cash ISA. From April 2027, cash ISA contributions will be capped at £12,000 for anyone under 65, with the remaining £8,000 needing to go into stocks and shares or other ISA types. So if you have been meaning to top up your cash ISA, this is the final window at the current limit.
Important: this is not financial advice. This article is for informational purposes only. Nothing in this post constitutes a recommendation to open any particular account, invest in any product, or take any specific financial action. Savings rates, ISA rules, and tax treatment can change at any time. CoolCuration is not authorised or regulated by the Financial Conduct Authority and cannot advise you on what is right for your circumstances. Always do your own research or speak to a qualified, independent financial adviser before making financial decisions. This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
Read more
April 11, 2026Comments are off for this post.
Chip Prize Saver vs Premium Bonds UK 2026: Which Is Actually Better?
Last updated: 10 September 2026
By Stiv · Design, technology and personal finance
Over 22 million people in the UK hold Premium Bonds, which makes them the nation's most popular savings product. Yet most holders have never weighed up Chip Prize Saver vs Premium Bonds side by side, and the numbers reward a closer look. Around 62% of Premium Bonds holders have never won a single prize, according to AJ Bell. The prize fund rate sits at 4.35% from the September 2026 draw, with each £1 bond facing odds of 21,000 to 1. NS&I has moved both twice this year. The rate ran at 3.30% with odds of 23,000 to 1 from April, went to 3.80% and 22,000 to 1 in July, then landed where it is now when NS&I announced the change on 18 August 2026.
Meanwhile, Chip's Prize Savings Account offers an alternative: a prize-draw savings account with a £10,000 grand prize every month and no interest at all. Both are a gamble on the return, not on the capital. You can hold either for a year, win nothing, and watch inflation eat the value of the money. We are not saying Premium Bonds are bad. Indeed, they are backed by the Treasury and pay tax-free prizes, which is a real advantage. However, if you have not compared them to anything in years, this is worth ten minutes of your time.
This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
Want to try the Chip Prize Saver?
Our Chip referral page carries the current new-customer bonus and the sign-up steps, kept up to date.
This article is for informational purposes only and does not constitute financial advice. It is not a recommendation to open, close, or switch any savings or investment product. Always do your own research or consider a qualified financial adviser before making financial decisions. CoolCuration is not authorised by the Financial Conduct Authority. Tax treatment depends on individual circumstances and may change. All product details were verified at the time of writing but may change, so always check the provider's website for current terms.
Read more
March 21, 2026Comments are off for this post.
Monzo vs Chase UK: Which Bank Account Is Better? (2026)
Last updated: 22 August 2026
By Stiv · Design, technology and personal finance
Affiliate disclosure: This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
After the bigger sign-up bonus?
Chase's refer-a-friend offer pays £50 when you join and deposit £1,000 within 30 days; our referral page walks you through it.
If you're weighing up Monzo vs Chase in 2026, you're in good company. Both are app-only banks, both are free to open, and both promise to make managing your money less painful. However, once you dig past the slick onboarding screens, the two take noticeably different approaches to savings, cashback and everyday features.
Chase (a trading name of J.P. Morgan Europe Limited) lures new customers with a boosted saver rate and 2% cashback on everyday spending. Monzo, the UK's original fintech darling, counters with powerful budgeting tools, paid plan perks like a free Railcard, and one of the most feature-rich banking apps on the market.
Below, we break down every meaningful difference so you can pick the one that actually fits your life. We also link to both referral offers if you want a bonus for signing up.
Comparing Monzo with more than Chase? I have also put it against Starling and Zopa's Biscuit, and my Monzo guides hub collects every Monzo guide in one place.
Read more
December 15, 2020Comments are off for this post.
Airtime Rewards Review UK: Is It Worth It?
Last updated: 10 June 2026
By Stiv · Design, technology and personal finance
This is an opinion piece. Views expressed are the author's own and do not constitute professional advice.
This article contains affiliate or referral links. If you click through and sign up I may earn a commission or referral bonus at no extra cost to you. It does not affect my editorial view.
This Airtime Rewards review covers everything we think you need to know about one of the UK's most effortless cashback apps. Link a card, spend as normal, and watch credit build up towards your phone bill. It sounds almost too simple to be true, but after using it for years we can confirm: it actually works. We also have a referral code that gets you up to a £5 bonus when you join and spend £5 within 7 days.
Cool Factor: 4/5 — Stone cold
Want the Airtime Rewards bonus?
Our referral page has the current code and the steps to claim up to a £5 bonus when you join and spend £5 within 7 days.
Read moreFollow us: Instagram
Copyright 2026 CoolCuration | Privacy Policy | Cookie Policy | Affiliate Disclosure | Cool Factor
-----------
We are proud supporters of a safer more private internet via encouraging people to use Brave browser and are actively taking on Spammers as part of ProjectHoneypot. This site is hosted on servers that run on 100% renewable energy in the UK thanks to GreenWebHosting.
This site contains affiliate links, including to Amazon.com and Amazon.co.uk. We may earn a commission if you make a purchase or sign up for a service via these links, at no extra cost to you. All offers and promotions are accurate at the time of publication but are subject to change or withdrawal by the businesses featured. We cannot guarantee their continued availability. Read our full affiliate disclosure.
Reviews and opinions on CoolCuration reflect the personal experience of our writers at the time of publication. They are not professional endorsements and your experience may differ. Scores use our Cool Factor rating system and are given independently of any commercial relationship.
All content on CoolCuration is provided for informational and entertainment purposes only. It does not constitute financial advice, investment recommendations or an endorsement of any product or service. We are not authorised by the Financial Conduct Authority and do not offer personalised financial guidance. You should always do your own research or consult a qualified financial advisor before making any financial decisions.