Bank Rate is up to 4% and the Autumn Budget is in. What changes for your mortgage, savings, investments and energy bill, and when, with every figure sourced.

October 21, 2026Comments are off for this post.
Best Easy Access Savings Accounts UK: October 2026 Rates
Last updated: 15 November 2026. I checked every rate on this list of the best easy access savings accounts on the provider's own website on 28 October 2026, and rechecked the referral offers and Chip's three accounts on 15 November.
By Stiv · Design, technology and personal finance
Affiliate disclosure: This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
This is not financial advice, and CoolCuration is not authorised by the Financial Conduct Authority. Every rate here is variable and can change after I checked it, so confirm the rate on the provider's own page before you move any money.
Five sign-up bonuses worth knowing about
None of these accounts tops the rate table, but each one pays something extra if you join through a referral link. Here is what each asks of you, and my referral pages have the steps and the current terms.
- Sidekick, £25: open a savings account, pay in £1,000 and hold it for three months. Sidekick referral code
- Chase, £50: open your first Chase account, activate a code in the app and pay in £1,000 within 30 days. Chase refer a friend code
- Lloyds, £30: open a new Lloyds current account through a referral link, as someone who has never banked with Lloyds. Lloyds referral link
- Zopa, £20: open a Biscuit current account and make three card payments within 30 days. Zopa Biscuit referral
- Tembo, £10 to £1,000: open a Cash ISA, Lifetime ISA or HomeSaver and pay in £500 within 30 days. Tembo draws the reward at random, and 95% of rewards are £10. Tembo referral page
Easy access savingsOctober 2026 rates
The top easy access rates, and what each pays once its bonus ends
The best easy access savings accounts this month pay up to 5.00% AER, the Annual Equivalent Rate, which is the rate after a year of interest on interest. But almost every account near the top gets there with a bonus that lasts three, six or twelve months. So I took 20 accounts, from savings apps and challenger banks to the big high street names, and worked out what £10,000 actually earns in each one over the first year and the year after.
Read more
September 29, 2026Comments are off for this post.
Is Monzo Max Worth It? I Priced the Three Policies
Last updated: 21 September 2026. I checked every Monzo figure and every comparison price on this page that day.
By Stiv · Design, technology and personal finance
Affiliate disclosure: This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
This is not financial advice, and CoolCuration is not authorised by the Financial Conduct Authority (FCA), the UK's financial regulator. I pay for Perks and have never held Max. So the verdict below is arithmetic from Monzo's own plan pages, its three policy booklets and published prices, rather than a year of living with the plan.
Opening a Monzo account first?
Every Monzo plan sits on top of a Monzo current account. My referral page has the live offer and the steps to claim it.
Monzo plans2026 edit
Worth it if you would buy two of the three policies anyway
Is Monzo Max worth it? Only if you would otherwise pay for at least two of the three insurance policies it bundles. Max costs £10 a month more than Perks, which comes to £120 a year. For that, it adds worldwide travel insurance, worldwide phone insurance and UK and Europe breakdown cover. I priced standalone versions of all three and they came to £290.66 a year. A household that needs all three therefore comes out well ahead. By contrast, someone who needs only one of them does not.
Still weighing up the Monzo range? My Monzo guides hub collects the lot, including the price rise, the Perks verdict and the Perks vs Max comparison.
Read more
September 15, 2026Comments are off for this post.
Monzo Perks vs Max: Which Plan Should You Pay For?
The gap between Monzo Perks and Max is £10 a month, and it buys three insurance policies. Priced honestly against buying them separately.
September 2, 2026Comments are off for this post.
Is Monzo Perks Worth It? A Year of Paying for It
A year of paying £9 a month for Monzo Perks, with the honest maths on what I actually claim and what earns nothing.
August 22, 2026Comments are off for this post.
Monzo Perks and Max Price Increase 2026: Every New Price
Monzo Perks goes from £7 to £9 a month and Max from £17 to £19. Here are all the new plan prices, the dates that matter, and the honest maths.
August 11, 2026Comments are off for this post.
Sprive Prize Draw Explained: How to Enter and What You Win
Sprive's "win £2,000 a week" headline is technically true and quietly misleading. The Sprive prize draw is a referral draw, not an overpayment one, and most entrants take home £5 a referral paid straight to their lender. Three draws are live right now, including £10,000 via Wayfair until 31 October. Here is the honest arithmetic on all three, plus the ones that closed.
July 25, 2026Comments are off for this post.
Best Free Budgeting Apps UK 2026
The best free budgeting apps in the UK for 2026, compared: what each free tier really includes, what is paywalled, and who each app suits.
July 20, 2026Comments are off for this post.
That Mortgage App on the Channel 4 Advert? It’s Sprive
Last updated: 13 October 2026
By Stiv · Design, technology and personal finance
I have used Sprive since October 2021, making regular overpayments through the app, first on a Nationwide mortgage and now on a Halifax one.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
This is not financial advice. It is one homeowner's experience, shared to help you make your own call.
So you spotted the Sprive advert on the telly and wondered what that mortgage app actually is. Here is the short answer: yes, the mortgage app on the Channel 4 advert is Sprive, and it helps you chip away at your mortgage a little faster. Below, I explain what it does, whether it is legit, and what it is like to use.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Want to try the app from the advert?
The current Sprive sign-up offer and how to claim it are kept up to date on our referral page.
Just seen the advert? The app behind it is explained below. For every Sprive guide in one place, see our Sprive guides hub.
Read more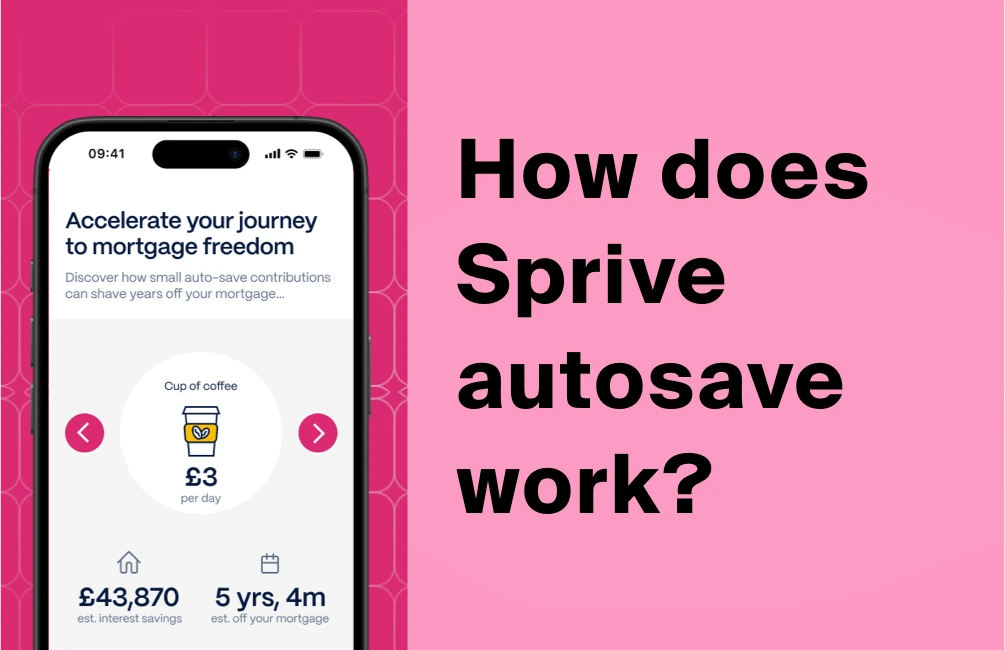
June 22, 2026Comments are off for this post.
How Does Sprive AutoSave Work?
Sprive AutoSave2026 Guide
How Sprive AutoSave decides what to move each month
Last updated: 13 October 2026
By Stiv · Design, technology and personal finance
I have overpaid my mortgage through Sprive since October 2021, with Nationwide and now Halifax, making regular overpayments through the app. Because of that, this guide to Sprive AutoSave comes from steady real use rather than a quick demo.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
This is general information, not financial advice. Sprive deals with your mortgage, so your circumstances matter and it is worth doing your own research.
Your home may be repossessed if you do not keep up repayments on your mortgage.
So what actually happens when you switch on Sprive AutoSave? In short, you set an amount, and each month it quietly moves that money into a holding pot inside the app, ready for your mortgage. Above all, you stay in control, because nothing reaches your lender until you tap to send it. Below, I walk through exactly how Sprive AutoSave works, where the money sits, and how to pause or switch it off, with notes from my own use since 2021.
Setting up AutoSave? The walkthrough is below. For every Sprive guide in one place, see our Sprive guides hub, updated as the app changes.
Read moreFollow us: Instagram
Copyright 2026 CoolCuration | Privacy Policy | Cookie Policy | Affiliate Disclosure | Cool Factor
-----------
We are proud supporters of a safer more private internet via encouraging people to use Brave browser and are actively taking on Spammers as part of ProjectHoneypot. This site is hosted on servers that run on 100% renewable energy in the UK thanks to GreenWebHosting.
This site contains affiliate links, including to Amazon.com and Amazon.co.uk. We may earn a commission if you make a purchase or sign up for a service via these links, at no extra cost to you. All offers and promotions are accurate at the time of publication but are subject to change or withdrawal by the businesses featured. We cannot guarantee their continued availability. Read our full affiliate disclosure.
Reviews and opinions on CoolCuration reflect the personal experience of our writers at the time of publication. They are not professional endorsements and your experience may differ. Scores use our Cool Factor rating system and are given independently of any commercial relationship.
All content on CoolCuration is provided for informational and entertainment purposes only. It does not constitute financial advice, investment recommendations or an endorsement of any product or service. We are not authorised by the Financial Conduct Authority and do not offer personalised financial guidance. You should always do your own research or consult a qualified financial advisor before making any financial decisions.