InvestEngine vs Trading 212 on the same ETF pot: fees, currency charges, cash interest, ISAs and Pies, from someone who uses both with real money.

October 15, 2026Comments are off for this post.
Monzo Invest vs Freetrade vs Lightyear: Which App Costs Less?
Last updated: 15 October 2026. I checked every fee in this Monzo Invest vs Freetrade comparison on each provider's own site on 14 October 2026.
By Stiv · Design, technology and personal finance
Affiliate disclosure: This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Not financial advice. This comparison is information, not a personal recommendation, and CoolCuration is not authorised by the Financial Conduct Authority. Nothing here tells you which account to open or what to buy. If you are unsure, speak to a qualified financial adviser. MoneyHelper explains how to choose one.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results.
Want a free share with Freetrade?
Freetrade picks the refer-a-friend share at random, worth £10 to £100, and the cheaper shares come up far more often. The steps and conditions are on my referral page.
See the Freetrade free share terms
More on Monzo. My Monzo guides hub covers the bank account, the paid plans and the savings pots alongside the investing side.
Investing appsHead to head
Monzo Invest, Freetrade and Lightyear, priced in pounds
If you already bank with Monzo, the easiest place to start investing is the tab you already have open. This Monzo Invest vs Freetrade comparison, with Lightyear as the third app, asks what staying put costs you. So I priced all three on the same jobs. That means the yearly fee on a £2,000 and a £20,000 pot, the charge for buying US shares, and the accounts each one will open. In short, Monzo charges £50 a year to hold £20,000. Freetrade's free plan and Lightyear charge nothing to hold it, but they bill you every time pounds become dollars.
Read more
October 9, 2026Comments are off for this post.
Best ETF Platform UK 2026: What It Really Costs to Hold ETFs
Which is the cheapest way to hold ETFs in the UK? I priced eight platforms on the same job, on a £2,000 pot and a £20,000 one, and the ranking flips.
September 21, 2026Comments are off for this post.
Best Managed Investment Platforms UK: 7 Compared
Seven UK managed investment platforms ranked on what they really cost, from J.P. Morgan Personal Investing to Monzo. All-in fees from 0.45% to 0.97%, every figure checked 10 September 2026.
April 8, 2026Comments are off for this post.
What Is Investment Risk? A Beginner’s Guide for 2026
What is investment risk UK? Learn the types of risk, how to manage them, and where to start investing with confidence. Beginner-friendly guide.
March 31, 2026Comments are off for this post.
Dividend Tax Rise 2026 UK: New Rates, Who Pays More and How to Shelter
Last updated: 9 June 2026
By Stiv · Design, technology and personal finance
CoolCuration is not authorised by the Financial Conduct Authority. This article is for informational purposes only and does not constitute financial or tax advice. Tax rules can change and their effects vary based on individual circumstances. Always do your own research or speak to a qualified tax adviser or accountant before making decisions.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results.
From 6 April 2026, UK dividend tax rates are rising by 2 percentage points at the basic and higher rates. If you receive dividends on shares or funds held outside an ISA or pension, your tax bill is going up. Here is what has changed, who is affected, and what you can do about it.
Read more
March 17, 2026Comments are off for this post.
Overpay Mortgage or Invest? UK Guide to the Right Call (2026)
Last updated: 13 October 2026
By Stiv · Design, technology and personal finance
We faced this decision ourselves. Since October 2021 I've overpaid my mortgage every month through Sprive, first with Nationwide and now with Halifax, and the total reached £10,237.41 by 13 October 2026. This guide covers how we thought through the trade-off and what factors are worth considering.
Should you overpay your mortgage or invest the spare cash instead? It's one of the biggest personal finance questions UK homeowners face right now, and the answer isn't as obvious as either side would have you believe. With the Bank of England base rate at 4% (raised from 3.75% on 5 November 2026, per the Bank of England), average two-year fixed mortgage rates around 5.64% as of early June 2026 (source: Moneyfacts), and top savings accounts paying around 4.75%, the maths is closer than it has been in years. This guide walks through the key factors, the trade-offs, and a practical framework to help you decide what makes sense for your situation. Our free mortgage overpayment calculator now also has a compare-to-savings toggle, so you can run both sides of one of those scenarios in seconds.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them. This is information, not financial advice, and CoolCuration is not authorised by the Financial Conduct Authority.
The Sprive bonus, if overpaying wins
Should the overpayment side win out for you, the current Sprive welcome offer lives on our referral page.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results.
Read more
March 16, 2026Comments are off for this post.
Best Investment ISA 2026 – Top Picks Before the Deadline
Last updated: 31 October 2026
By Stiv · Design, technology and personal finance
Best investment ISA2026 Edit
The best investment ISA for every kind of UK investor
Finding the best investment ISA in 2026 really comes down to one question: what kind of investor are you? So instead of crowning a single winner, this guide matches the main UK stocks and shares ISA platforms to the people they actually suit, then compares them on the things that move the needle: fees, FX costs, choice of investments and how easy each one is to use.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Not financial advice. This article is for information only and reflects personal experience, not a recommendation. Because investing carries risk, always do your own research or speak to a qualified financial adviser before you act.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results.
The low-cost ISA we track most
For transparency, Lightyear is the low-cost Stocks and Shares ISA we use and follow most closely, so you will see it referenced throughout. It is also the account behind our living can AI turn £1,000 into £10,000 experiment. You can check its current ISA details and any live offer on our referral page before you decide anything.
Read more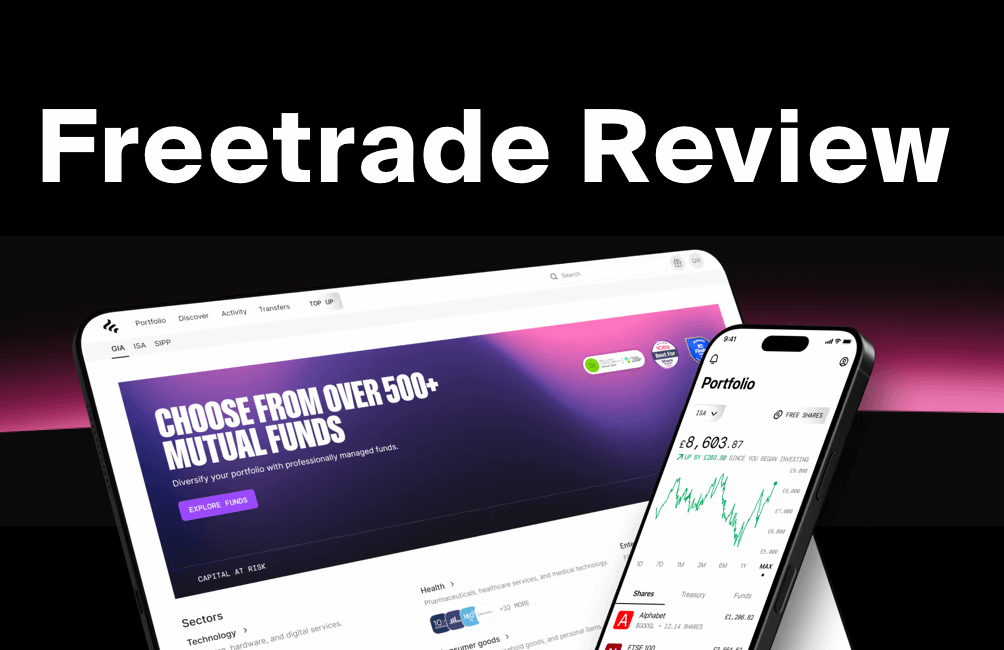
March 7, 2026Comments are off for this post.
Freetrade Review UK: Honest Pros, Cons and Verdict (2026)
Last updated: 7 October 2026
By Stiv · Design, technology and personal finance
This is an opinion piece. Views expressed are the author's own and do not constitute financial advice.
Cool Factor: 4/5
This Freetrade review UK covers everything you need to know before opening an account: plans, fees, what you can invest in, what real users say on Trustpilot, and where the app falls short. Freetrade has grown into one of the UK's most popular investing apps since the company was founded in 2016. However, popularity and quality are not always the same thing. This review is based on my own experience using the app, and I have dug into the plans, fees and real user feedback so you don't have to.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results.
Want a free share with Freetrade?
Freetrade's refer-a-friend deal gives a free share when you join, subject to qualifying conditions. The current offer and full terms are kept up to date on our referral page.
Get a free share with Freetrade
Read more
February 17, 2026Comments are off for this post.
Monzo investment fees cut: what it means and whether it’s worth it
Last updated: 9 June 2026
By Stiv · Design, technology and personal finance
Quick take: Monzo investment fees were cut in February 2026 from 0.45% to 0.25% a year (or from 0.35% to 0.20% on certain paid plans). If you're a smaller-balance, set-and-forget investor, Monzo just got a lot more competitive. If you're fee-optimising at higher balances, fund costs and fee caps still matter.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results. This is not financial advice.
Monzo has made a change that actually matters: the platform fee for Monzo Investments is now 0.25% per year (and 0.20% if you're on eligible paid plans), down from 0.45% (or 0.35% for Plus and Premium customers) before the February 2026 fee cut. Fees accrue daily and get collected monthly from your investment account. That's the "Monzo fee" bit, not the fund manager's own fee (more on that below).
Want the rest of the Monzo investing picture? My Monzo guides hub has the full Monzo Investments review, the paid plans and the savings pots.
Read moreFollow us: Instagram
Copyright 2026 CoolCuration | Privacy Policy | Cookie Policy | Affiliate Disclosure | Cool Factor
-----------
We are proud supporters of a safer more private internet via encouraging people to use Brave browser and are actively taking on Spammers as part of ProjectHoneypot. This site is hosted on servers that run on 100% renewable energy in the UK thanks to GreenWebHosting.
This site contains affiliate links, including to Amazon.com and Amazon.co.uk. We may earn a commission if you make a purchase or sign up for a service via these links, at no extra cost to you. All offers and promotions are accurate at the time of publication but are subject to change or withdrawal by the businesses featured. We cannot guarantee their continued availability. Read our full affiliate disclosure.
Reviews and opinions on CoolCuration reflect the personal experience of our writers at the time of publication. They are not professional endorsements and your experience may differ. Scores use our Cool Factor rating system and are given independently of any commercial relationship.
All content on CoolCuration is provided for informational and entertainment purposes only. It does not constitute financial advice, investment recommendations or an endorsement of any product or service. We are not authorised by the Financial Conduct Authority and do not offer personalised financial guidance. You should always do your own research or consult a qualified financial advisor before making any financial decisions.