My AI stock picking experiment: can four AI models grow $1,000 into $10,000 on Lightyear? I post honest, not-advice weekly updates.
June 3, 2026Comments are off for this post.
Can AI Turn $1,000 Into $10,000? My AI Stock Picking Experiment
May 10, 2026Comments are off for this post.
How To Read Your Energy Bill UK: The 2026 Guide
Last updated: 27 August 2026
By Stiv · Design, technology and personal finance
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Your energy bill arrives every month. You glance at the total, wince, and close it. Most of us have no clue whether the number is right, whether we're overpaying, or what any of the line items actually mean. So here's how to read energy bill statements properly, in about five minutes flat.
Honestly, we stared at our own bills for nearly three years before any of it clicked. The numbers looked made up. The terminology was designed by people who hate clarity. Once you understand the four or five lines that actually matter, you can immediately tell if you're overpaying, if your tariff is competitive, and whether switching would save you money. This is the guide we wish we'd had back then.
Energy prices, tariffs, and government support schemes change regularly. All figures in this post are verified as of 27 August 2026. Always check your supplier's website or Ofgem for the latest information.
Read more
May 9, 2026Comments are off for this post.
XTB App Review UK 2026: One Star Opinion (1/5)
Last updated: 10 June 2026
By Stiv · Design, technology and personal finance
I have used investing apps for over a decade, including Freetrade, Lightyear, Trading 212, Interactive Brokers and JPMorgan Personal Investing. This XTB app review is based on real, recent first-hand use on iPhone over the past few weeks.
This is an opinion piece. Views expressed are my own personal experience and observations. Other XTB customers have reported very different experiences, both better and worse, and you can read those views directly on the App Store, Google Play and Trustpilot. Nothing in this review constitutes professional, financial or legal advice, nor an allegation of wrongdoing by XTB. Capital is at risk when investing.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them. This post does not contain any XTB referral links; where alternative brokers are mentioned, those links may include CoolCuration referral codes. We have no referral relationship with XTB and do not benefit financially from XTB itself.
Capital at risk. The value of investments can go down as well as up and you may get back less than you invested. Past performance is not a reliable indicator of future results.
Cool Factor: 1/5
Welcome to our XTB app review. After spending the last few weeks battling with the broker's iOS app, surviving a verification process worthy of a Kafka novella, and being chased around the screen by stock notifications I never asked for, I have reached a personal verdict. It is not flattering. So if you have seen the ads and the free share offers, this XTB app review explains exactly what you would be signing up for, in my experience.
Read more
May 5, 2026Comments are off for this post.
Mortgage Overpayment Savings: How Much Could You Save? (2026)
Last updated: 13 October 2026
By Stiv · Design, technology and personal finance
I've overpaid my own mortgage through Sprive every month since October 2021, starting at £100 a month. This post is based on that real use and real numbers.
Most people know they should overpay their mortgage. Almost nobody knows by how much, or what it actually saves them. So we built a free mortgage overpayment calculator to find out. Then we ran our own numbers through it. The mortgage overpayment savings took us by surprise. We've since added a compare-to-savings toggle so you can see whether overpaying or saving the same money comes out ahead at your specific rates.
This article is for informational purposes only and does not constitute financial or mortgage advice. Mortgage products, rates, and overpayment terms vary by lender. Always check your lender's overpayment policy before making extra payments. This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them. Your home may be repossessed if you do not keep up repayments on your mortgage. CoolCuration is not authorised by the Financial Conduct Authority.
See your own overpayment savings
Our free calculator shows what your overpayments could save, and whether saving the cash instead would beat them.
Open the overpayment calculator
Read more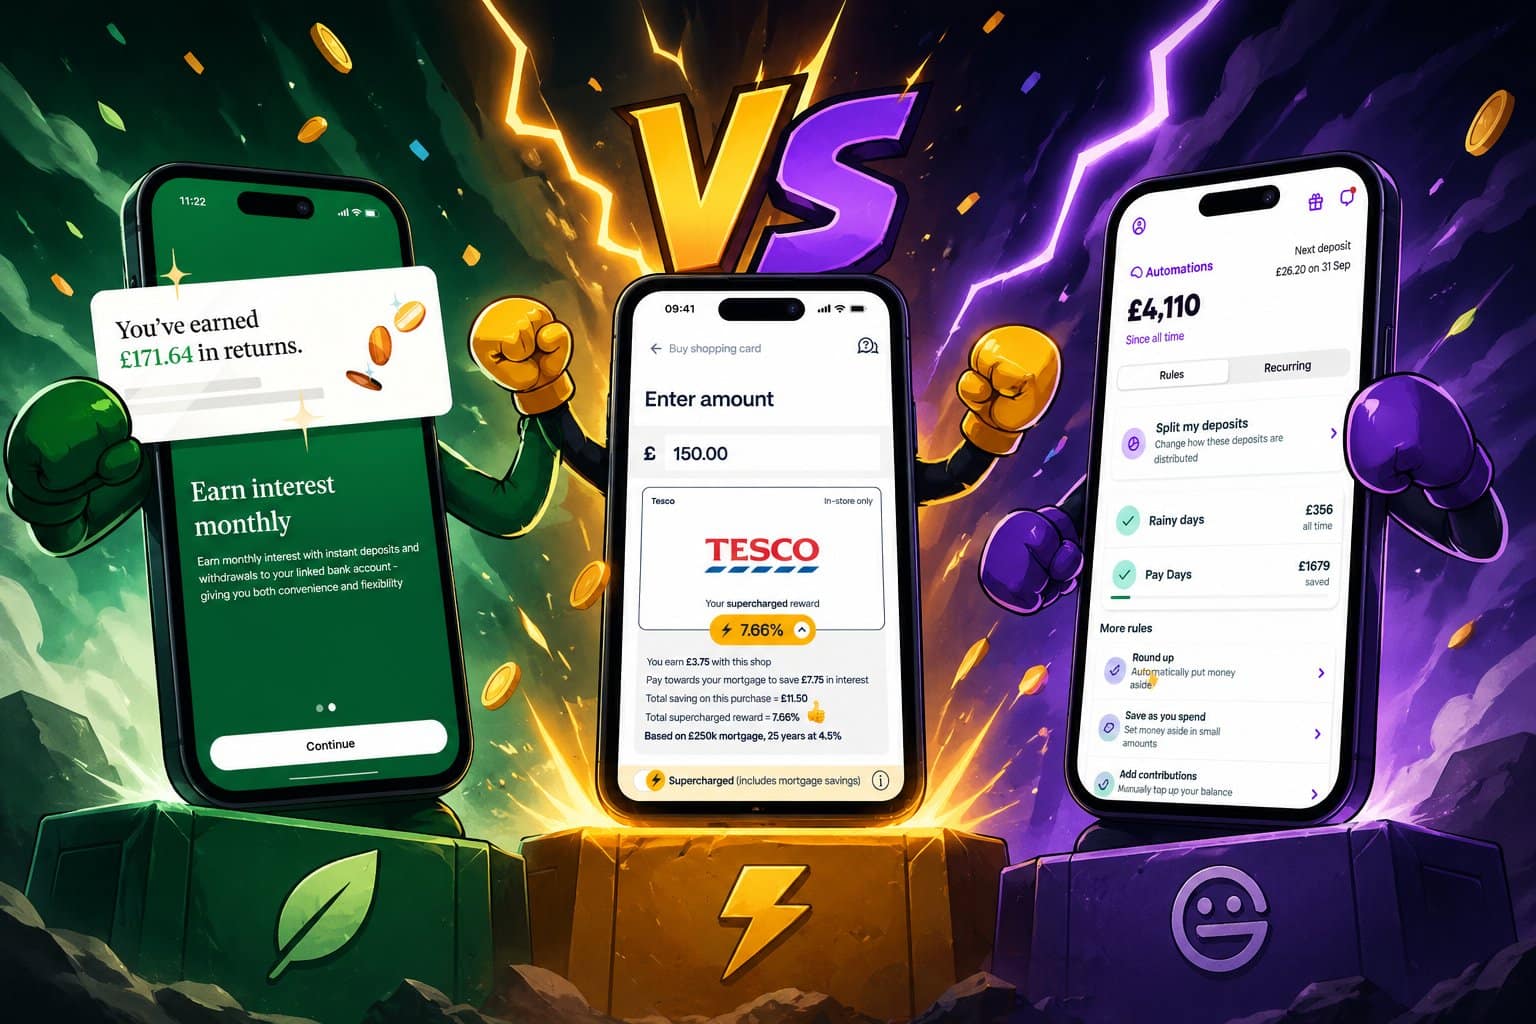
April 29, 2026Comments are off for this post.
Sprive vs Plum vs Chip: Honest Comparison (2026)
Last updated: 15 November 2026
By Stiv · Design, technology and personal finance
I've used Sprive since October 2021, making monthly overpayments on my mortgage through the app. This comparison is based on that real use alongside Chip and Plum.
Sprive vs Plum vs Chip is the question that keeps coming up whenever anyone in the UK talks about saving money automatically. All three apps promise to do the hard bit for you. But they are not the same thing, and picking the wrong one means you are either missing features you need or paying for ones you do not. Here is how they actually compare after months of using all three.
Between the team, we run all three. Sprive handles mortgage overpayments. Chip is our primary auto-saver. Plum runs alongside Chip so we can see how the two compare in real life. Each has earned its place on someone's home screen, but for very different reasons.
This article is for informational purposes only and does not constitute financial advice. Some apps in this comparison offer investing features, which carry risk including the possible loss of capital. Your home may be repossessed if you do not keep up repayments on your mortgage. CoolCuration is not authorised by the Financial Conduct Authority. This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Sprive's current sign-up offer
If Sprive ends up being your pick of the three, the latest welcome bonus is always on our referral page.
Comparing money apps? The three-way verdict is below. For everything we have written on Sprive in one place, see our Sprive guides hub.
Read more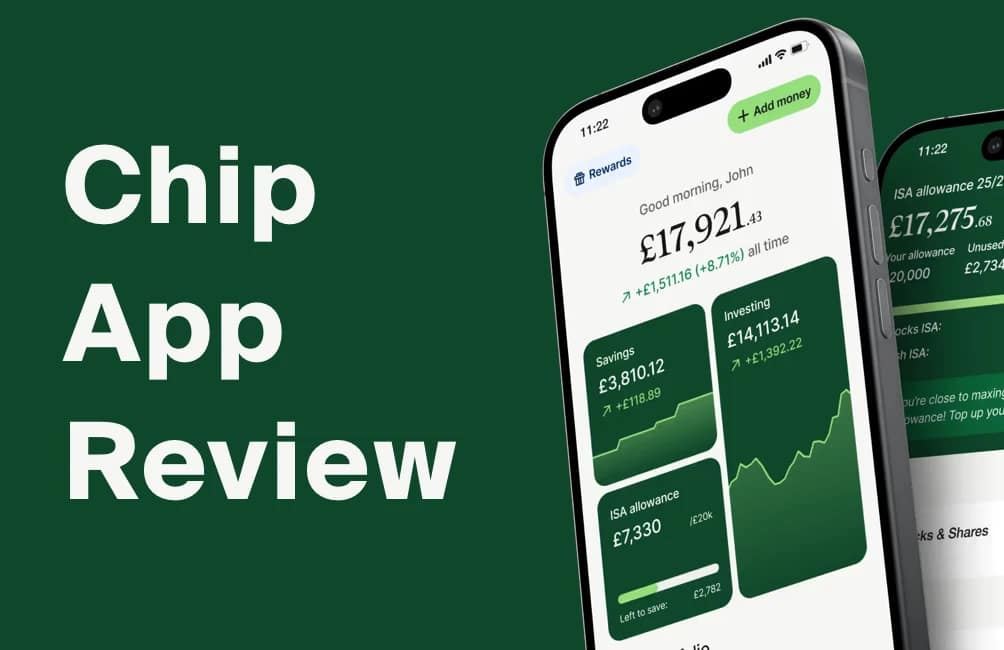
April 26, 2026Comments are off for this post.
Chip App Review UK 2026: 3 Years Tested, Rates, Prize Saver, Fees
Last updated: 15 November 2026
By Stiv · Design, technology and personal finance
This Chip app review UK draws on three and a half years of my personal daily use, starting 3 November 2022, across auto-save, the Instant Access Saver, Prize Savings, ChipX (briefly) and a Chip Stocks and Shares ISA.
This is an opinion piece. Views expressed are the author's own and do not constitute professional advice.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
This article is for informational purposes only and does not constitute financial advice. Some features of Chip involve investing, which carries risk including the possible loss of capital. Savings rates can change. Always do your own research or consult a qualified financial adviser. CoolCuration is not authorised by the Financial Conduct Authority.
Fancy trying Chip yourself?
The referral code and Chip's current referral terms are on our Chip referral page. Chip runs its referral offers in short windows, and the current one does not include a bonus for new customers.
Cool Factor
★★★★☆
4 out of 5 · Stone cold
My Chip app review UK is grounded in the actual ledger: £174.41 in interest earned, £180 in tax-free prize wins, £0.80 in investment returns, and three and a half years of daily use since November 2022. That is the unvarnished record of what I have personally taken out of Chip across four different account types. Below is what I kept, what I binned, what works, and the one quirk that still mildly irritates me.
Read more
April 22, 2026Comments are off for this post.
Best Apps to Save Money UK 2026: The Ones We Actually Use
Last updated: 15 November 2026
By Stiv · Design, technology and personal finance
There are hundreds of money-saving apps in the UK app stores. Most of them are rubbish. The best apps to save money are the ones we've tested over the past few years, narrowed down and kept on our phones because they actually work. No fluff, no apps we downloaded once and forgot about. Just the ones that earned a permanent spot.
Between the team we've got about 12 money apps installed. Half of them we actually use. The other half sit there judging us. We tried about 20 apps before settling on this list. Some were too fiddly. Some had great ideas but terrible execution. A couple were brilliant but shut down. These are the survivors.
This article is for informational purposes only and does not constitute financial advice. Some apps in this list offer savings and investment features. Your capital may be at risk. CoolCuration is not authorised by the Financial Conduct Authority. This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Our top money-saving pick
If you only set up one, make it Chip: it is the app that has quietly saved us the most by moving money before we miss it.
Read more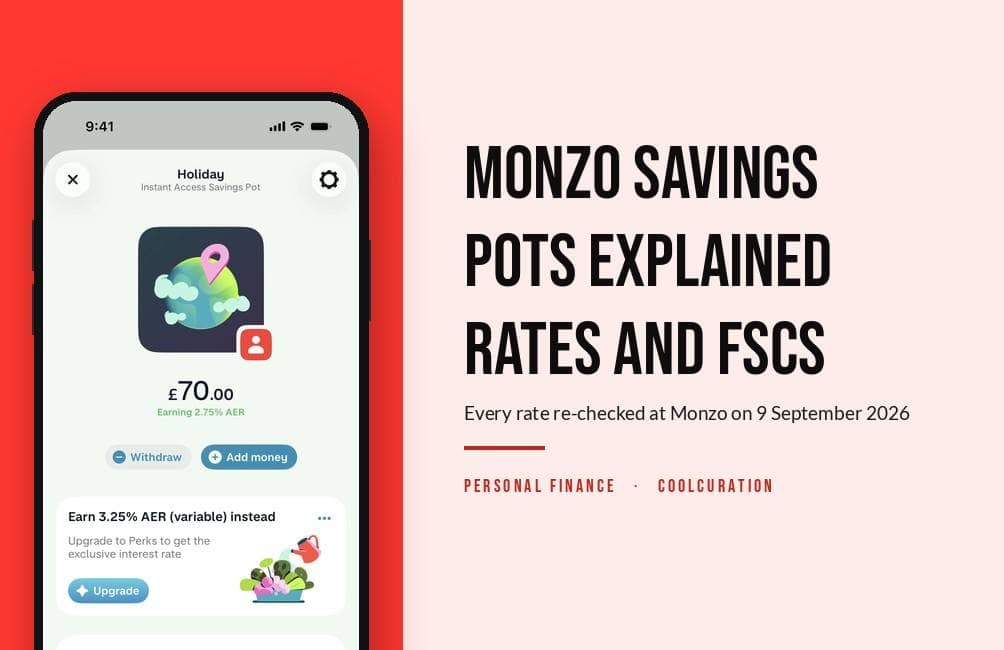
April 19, 2026Comments are off for this post.
Monzo Savings Pots Explained: Rates, FSCS Protection and How to Start (2026)
Last updated: 15 November 2026. I re-checked every Monzo savings pots rate against Monzo's own pages on 15 November 2026, after the Bank of England raised Bank Rate to 4%, along with the Chase, Chip, Zopa and Marcus rates it compares against.
By Stiv · Design, technology and personal finance
Monzo savings pots are one of the most useful things in UK banking. Yet plenty of people with a Monzo account still leave spare cash in the main balance, earning nothing. A pot takes about thirty seconds to set up. Better still, it starts earning the same day. No paperwork, no second app, no waiting.
I keep six or seven pots running at any one time. Bills, holiday, an emergency fund, two savings pots earning interest. Plus one labelled "don't touch" that I absolutely do touch. Below is what each type pays, what the higher rates cost, and where the money actually sits.
This article is for general information only and does not constitute financial advice. Savings rates are variable and change often. Always check the current rate in the Monzo app or at monzo.com first. CoolCuration is not authorised by the Financial Conduct Authority. This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Not on Monzo yet?
Sign up through my referral link. A random reward from £5, up to £50 (sometimes up to £100), arrives once you make your first card payment.
Want the wider Monzo picture? My Monzo guides hub has the account review, the paid plans and the investing side, all in one place.
Read more
April 18, 2026Comments are off for this post.
Best Savings Options for the New Tax Year UK 2026/27
Last updated: 15 November 2026
By Stiv · Design, technology and personal finance
Every April, we go through the same routine. The ISA allowance resets, savings rates shift, and there is a brief window where everyone actually pays attention to where their money is sitting. The best savings options for the new tax year are worth sorting now, before the motivation fades and another 12 months slip by. Here is what the CoolCuration team is doing with ours this year, along with a look at the platforms and accounts worth considering right now.
One change you no longer need to plan around: the cut to the cash ISA limit for under-65s, due in April 2027, was scrapped in the Autumn Budget on 28 October 2026. The full £20,000 can still go into a cash ISA. My Autumn Budget 2026 guide covers the savings tax rise that did go ahead.
Important: this is not financial advice. This article is for informational purposes only. Nothing in this post constitutes a recommendation to open any particular account, invest in any product, or take any specific financial action. Savings rates, ISA rules, and tax treatment can change at any time. CoolCuration is not authorised or regulated by the Financial Conduct Authority and cannot advise you on what is right for your circumstances. Always do your own research or speak to a qualified, independent financial adviser before making financial decisions. This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Read more
April 16, 2026Comments are off for this post.
When Should You Remortgage UK? Timing, Tips and What to Watch For (2026)
Last updated: 13 October 2026
By Stiv · Design, technology and personal finance
I remortgaged from Nationwide to Halifax in June 2026 and have overpaid my own mortgage through Sprive every month since October 2021. This guide draws on that real experience alongside verified market data.
Knowing when to remortgage UK is one of the most valuable financial moves you can make as a homeowner. Get it right and you could save thousands over the life of your deal. Get it wrong and you risk haemorrhaging money to your lender's standard variable rate while you scramble to sort a new deal. A surprising number of homeowners either leave it too late or jump too early and pay penalties they did not need to. Several of us on the CoolCuration team have remortgaged in the last couple of years, so this guide draws on real experience alongside verified market data.
This article contains affiliate and referral links, which are paid links. If you click one and buy or sign up, I earn a commission or referral bonus at no extra cost to you. Brands don't choose what I feature or what I say about them.
Important: This article is for informational purposes only and does not constitute financial or mortgage advice. CoolCuration is not authorised by the Financial Conduct Authority and does not provide regulated mortgage advice. Always consult a qualified mortgage adviser before making decisions about your mortgage. Your home may be repossessed if you do not keep up repayments on your mortgage.
Sprive welcome offer
Once the new deal is sorted and you turn to overpaying, the latest sign-up bonus is kept up to date on our referral page.
Check the current Sprive bonus
Read moreFollow us: Instagram
Copyright 2026 CoolCuration | Privacy Policy | Cookie Policy | Affiliate Disclosure | Cool Factor
-----------
We are proud supporters of a safer more private internet via encouraging people to use Brave browser and are actively taking on Spammers as part of ProjectHoneypot. This site is hosted on servers that run on 100% renewable energy in the UK thanks to GreenWebHosting.
This site contains affiliate links, including to Amazon.com and Amazon.co.uk. We may earn a commission if you make a purchase or sign up for a service via these links, at no extra cost to you. All offers and promotions are accurate at the time of publication but are subject to change or withdrawal by the businesses featured. We cannot guarantee their continued availability. Read our full affiliate disclosure.
Reviews and opinions on CoolCuration reflect the personal experience of our writers at the time of publication. They are not professional endorsements and your experience may differ. Scores use our Cool Factor rating system and are given independently of any commercial relationship.
All content on CoolCuration is provided for informational and entertainment purposes only. It does not constitute financial advice, investment recommendations or an endorsement of any product or service. We are not authorised by the Financial Conduct Authority and do not offer personalised financial guidance. You should always do your own research or consult a qualified financial advisor before making any financial decisions.